Fiscal vs monetary policy: who fought inflation, and what it did to your money
In October 2022, prices in the euro area were rising at 10.6% a year. That's the highest rate on record for the euro area. On that same day, the European Central Bank's main interest rate was 0.75%, and only four months earlier it had been below zero.
Over the next eleven months the ECB raised that rate to 4.0%. Meanwhile, governments across Europe were spending hundreds of billions on energy support and recovery plans. One institution was pressing the brake while others still had a foot near the accelerator.
That tug of war is the difference between fiscal policy and monetary policy.
Two ways to steer an economy
Fiscal policy is the government's budget. When a government spends more than it collects in taxes, it runs a deficit and borrows the difference, which pushes money into the economy. When it cuts spending or raises taxes, it pulls money out.
Monetary policy is the central bank's job. The ECB, the US Federal Reserve and the Bank of England (among others) set a short-term interest rate, and that rate ripples out to what banks charge for mortgages and pay on deposits. Central banks can also buy government bonds in bulk, which pushes long-term borrowing costs down.
A car is a fair picture. The government decides how much fuel goes in the tank, and the central bank works the brake and the accelerator pedal. Both change the speed, and they can work against each other.
The two levers differ in who pulls them and how fast. A budget has to pass a parliament, which can take months (or years, if you have watched a budget fight in Rome or Washington). A central bank can change its rate at the next meeting, and the ECB meets every six weeks.
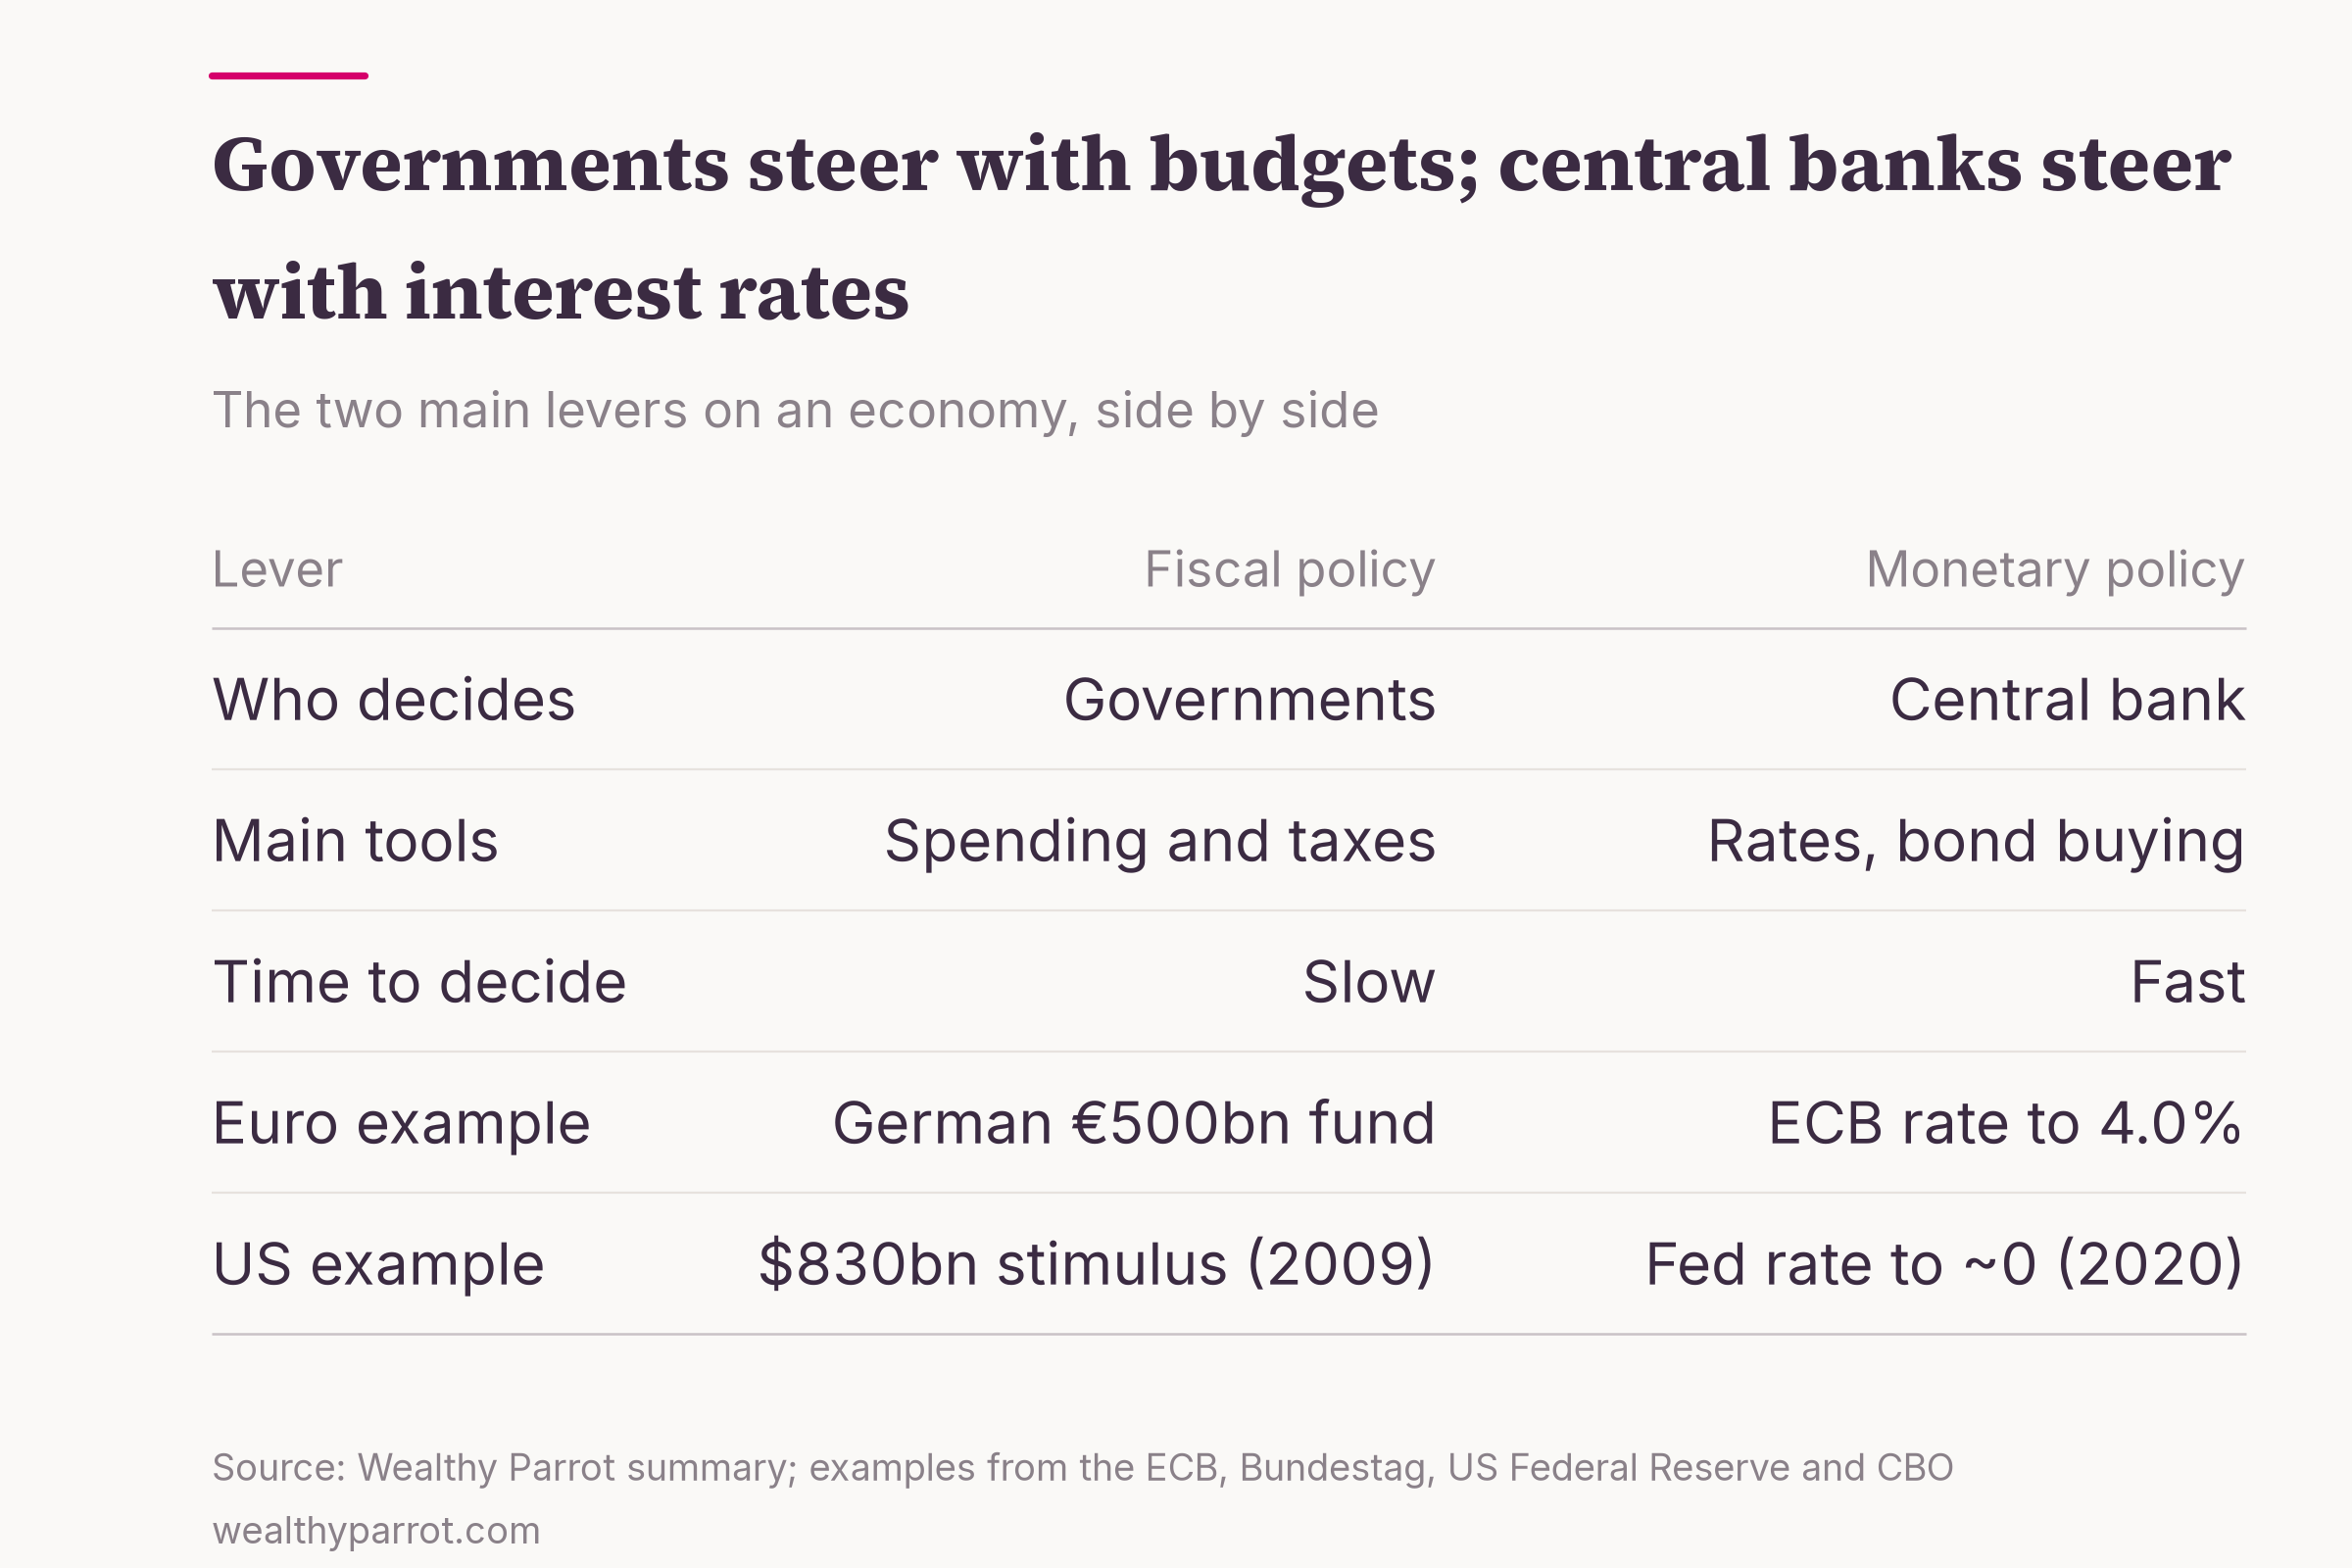
Central banks are also kept at arm's length from politicians on purpose. The EU treaties forbid the ECB from taking instructions from governments, and it aims for inflation of 2% over the medium term. The idea is simple. A finance minister facing an election would always prefer cheaper money, so the brake is handed to someone who doesn't face voters.
There is one more difference that matters for Europe. In the United States, one government and one central bank cover the same economy. In the euro area, one central bank sets rates for 21 countries, and each of those countries writes its own budget. Keep that in mind, because it explains half of what follows.
How much governments spent when Covid hit
In 2020, both levers were pulled at once, and harder than ever before in peacetime. The fiscal side came first in the headlines, so I'll start there.
The measure that captures it is the budget balance as a share of GDP. It compares how much a government spent beyond its income with the size of its economy. A deficit of 3% is ordinary. In 2020 the numbers went far past that.
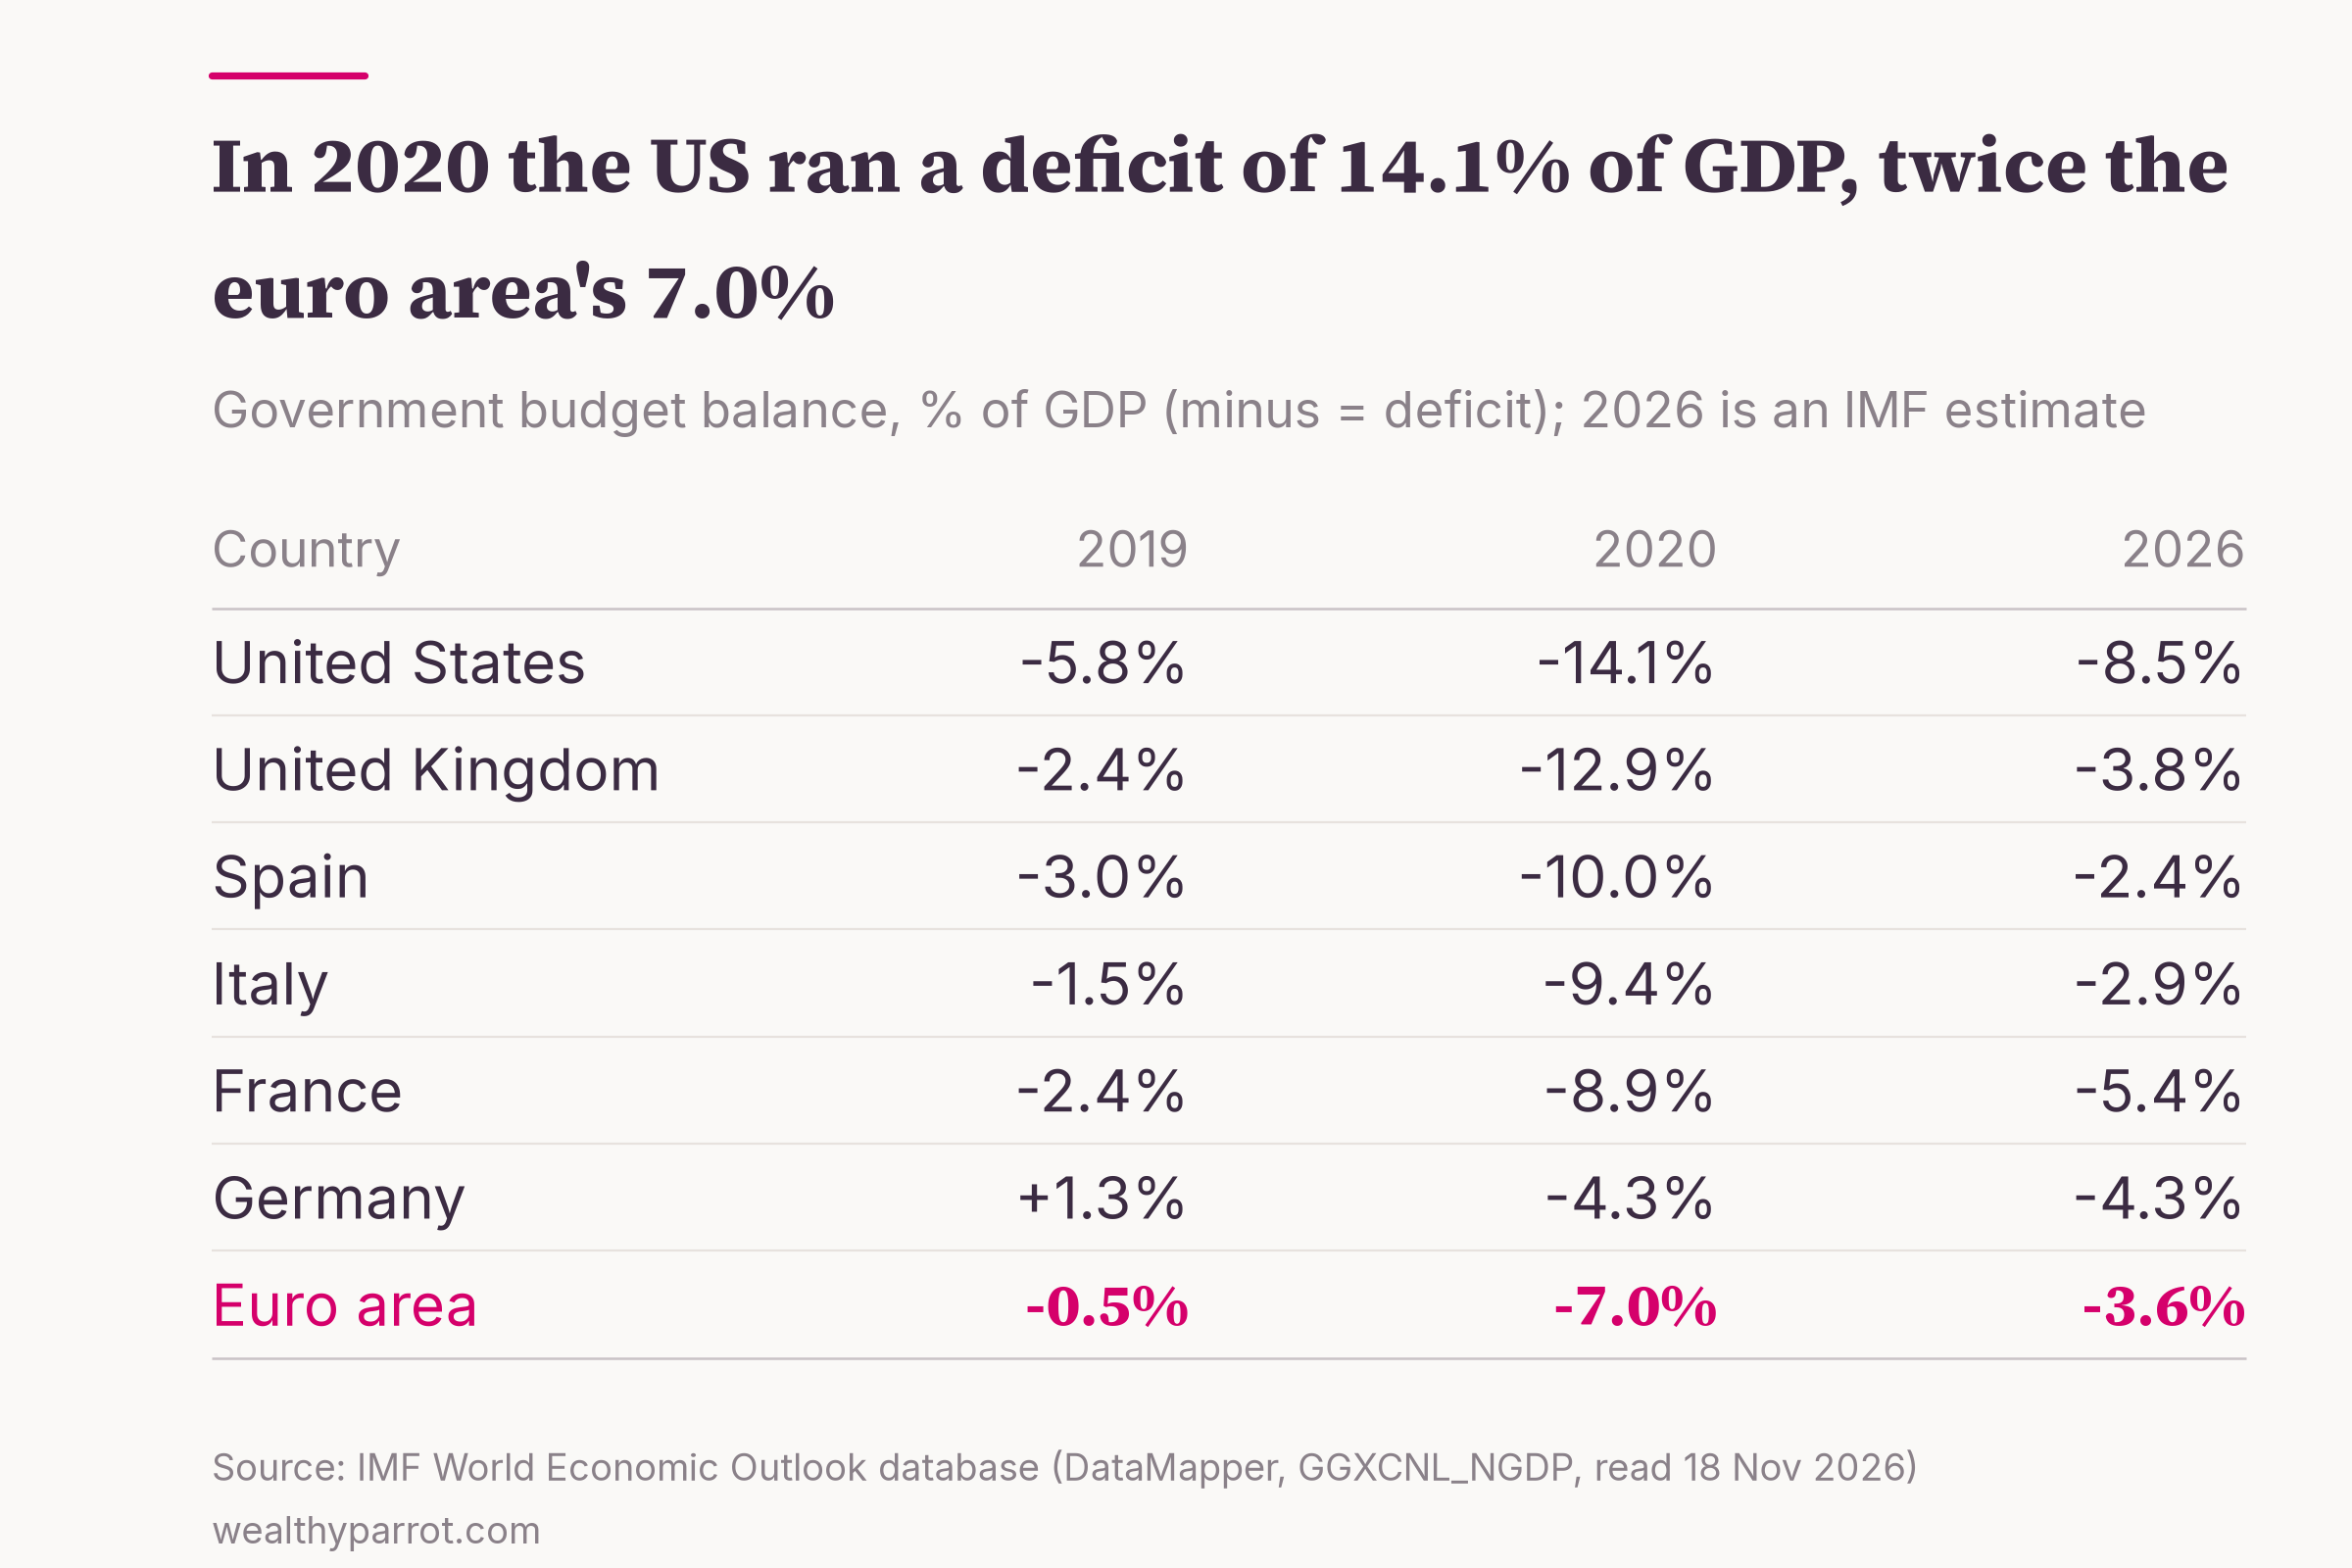
According to the IMF's World Economic Outlook database, the US ran a deficit of 14.1% of GDP in 2020, and the UK 12.9%. The euro area as a whole ran 7.0%, about half the American figure. Germany, which had a surplus of 1.3% in 2019, still only went to a deficit of 4.3%.
Part of the gap is how the money was spent. Many European countries paid firms to keep workers on reduced hours instead of sending out large cheques. The EU backed that approach with SURE, a loan scheme of up to €100 billion, of which €98.4 billion went to 19 member states to fund short-time work.
Then came the larger plan. NextGenerationEU, agreed in 2020, has a maximum envelope of €806.9 billion in grants and loans, and the European Commission expects to have borrowed up to €634 billion on markets by the end of 2026. It was the first time the EU borrowed together at that scale.
Fun fact: the EU plans to repay NextGenerationEU's debt between 2028 and 2058, so part of the 2020 rescue is still on the books when today's 30-year-olds retire.
For scale, the 2009 American stimulus after the financial crisis looked enormous at the time. The Congressional Budget Office put its cost at about $830 billion over 2009-2019, up from an original estimate of $787 billion. The 2020 deficits dwarfed it.
All that borrowing left a mark on debt. Per Eurostat, euro area government debt rose from 83.5% of GDP in 2019 to 96.3% in 2020, then eased back to 87.7% in 2025. Italy's debt has come most of the way back down, while France's was higher in 2025, at 115.7%, than in 2020.
How the ECB fought inflation
The monetary side started in the same month. In March 2020 the Fed cut its rate to a range of 0% to 0.25%. The ECB's deposit rate, which is what banks earn on money they park at the central bank, was already at -0.5%, so it had little room to cut, and it reached for its other tool.
That tool was the Pandemic Emergency Purchase Programme (PEPP). Starting in March 2020, the ECB committed to buy up to €1,850 billion of bonds, mostly government debt. Buying bonds pushes their prices up and their yields down, which kept borrowing cheap for governments that were running the deficits above.
Fun fact: from June 2014 to July 2022 the ECB's deposit rate was below zero, so for eight years banks paid the ECB to hold their spare cash (yes, really).
Then prices started to climb. Inflation was 2.2% in July 2021, 5.1% in January 2022 and 8.9% in July 2022. The ECB held its rate at -0.5% until July 2022, when it raised it for the first time since 2011.
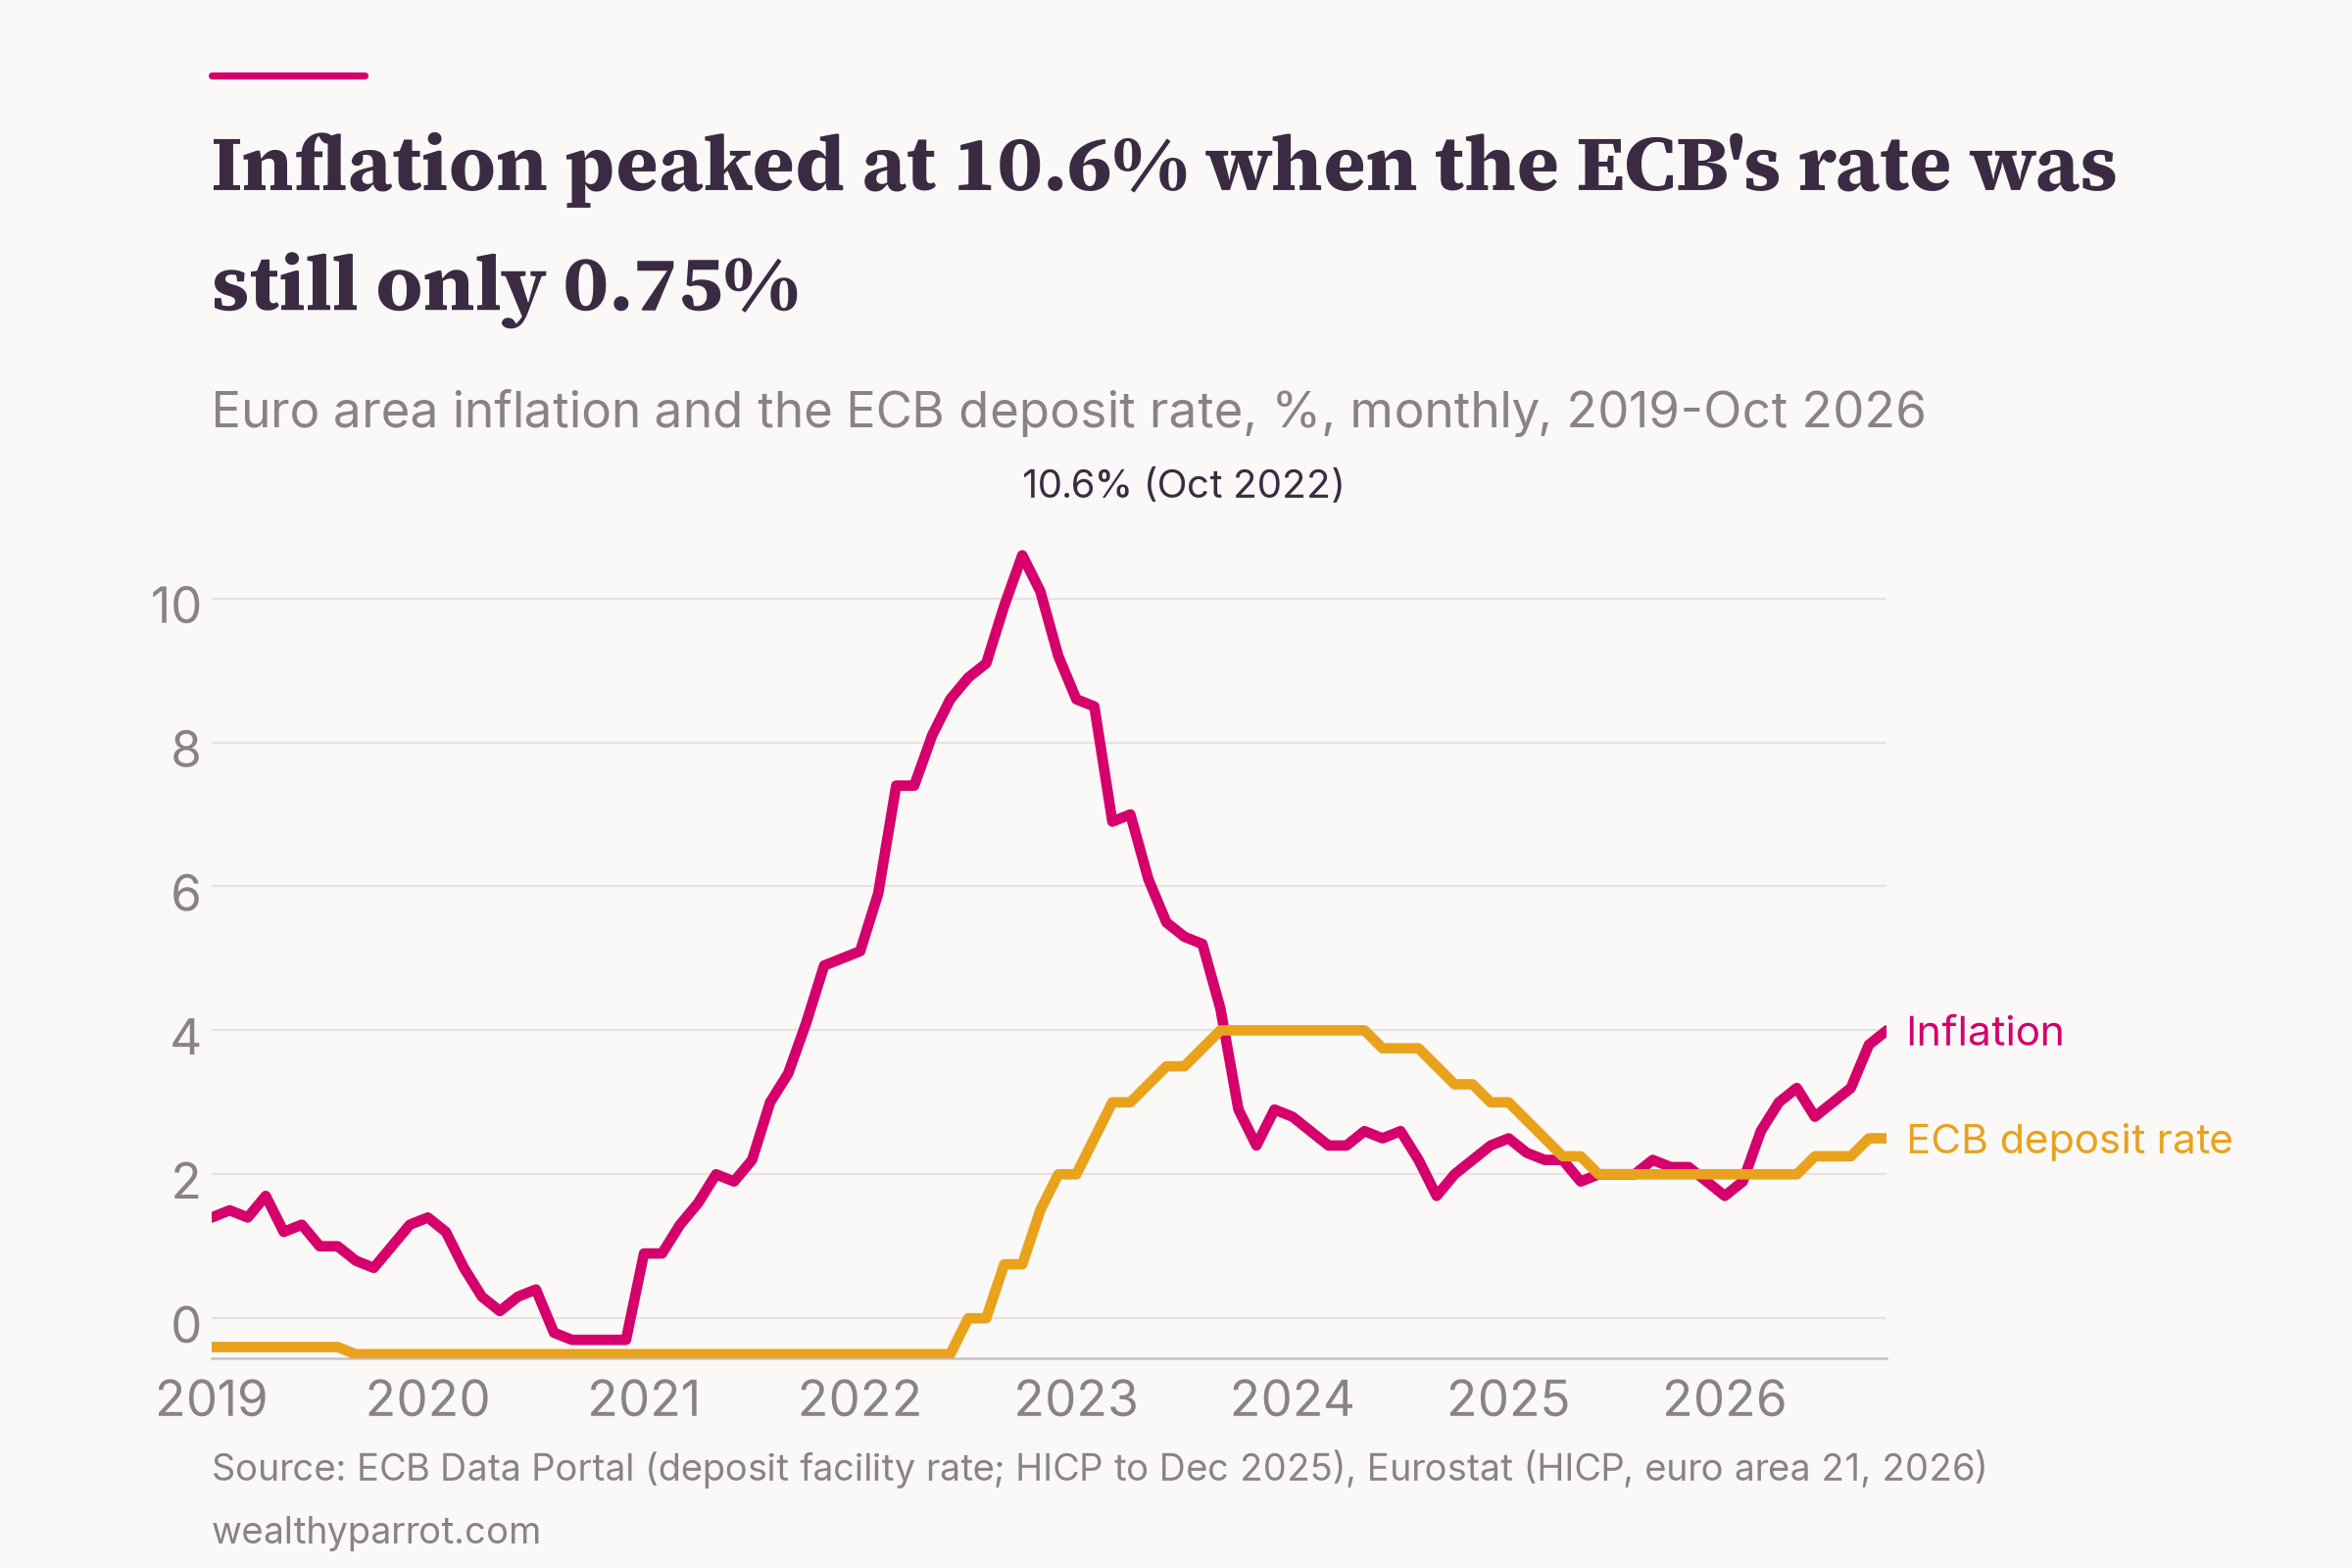
What followed was a rapid run of increases. The ECB raised the deposit rate ten times between July 2022 and September 2023, from -0.5% to 4.0%, according to the ECB's record of key interest rates. Across the Atlantic, the Fed went from near zero to an upper limit of 5.50% by July 2023.
Inflation came down, though the chart shows something worth noticing.
It peaked in October 2022, when the rate was still 0.75%. Much of the 2022 surge came from energy. In October 2022, energy prices in the euro area were 41.5% higher than a year before, after Russia's invasion of Ukraine. Interest rates do little to the price of gas in the short run.
By the time the rate reached 4.0% in September 2023, inflation was 4.3%, and two months later it was 2.4%.
How much credit the ECB deserves for that fall is still argued over, and I won't pretend to settle it here. The data does show the order of events. Energy prices eased, rates rose, and inflation returned close to the 2% target by 2025.
The ECB then cut eight times between June 2024 and June 2025, bringing the deposit rate to 2.0%. It held there for a year. In 2026 inflation picked up again, reaching 4.0% in October according to Eurostat, and the ECB raised the rate to 2.25% in June and 2.5% in September.
Why the euro area is a special case
Here is the structural problem I mentioned earlier. The ECB sets one interest rate for 21 countries. Each country's government borrows on its own, in euros, at whatever rate investors demand.
Investors demand more from some than from others. The cleanest measure is the spread, which is the yield on Italy's 10-year government bond minus the yield on Germany's. Both bonds are in euros, so the gap is the extra return investors want for holding Italian debt over German debt.
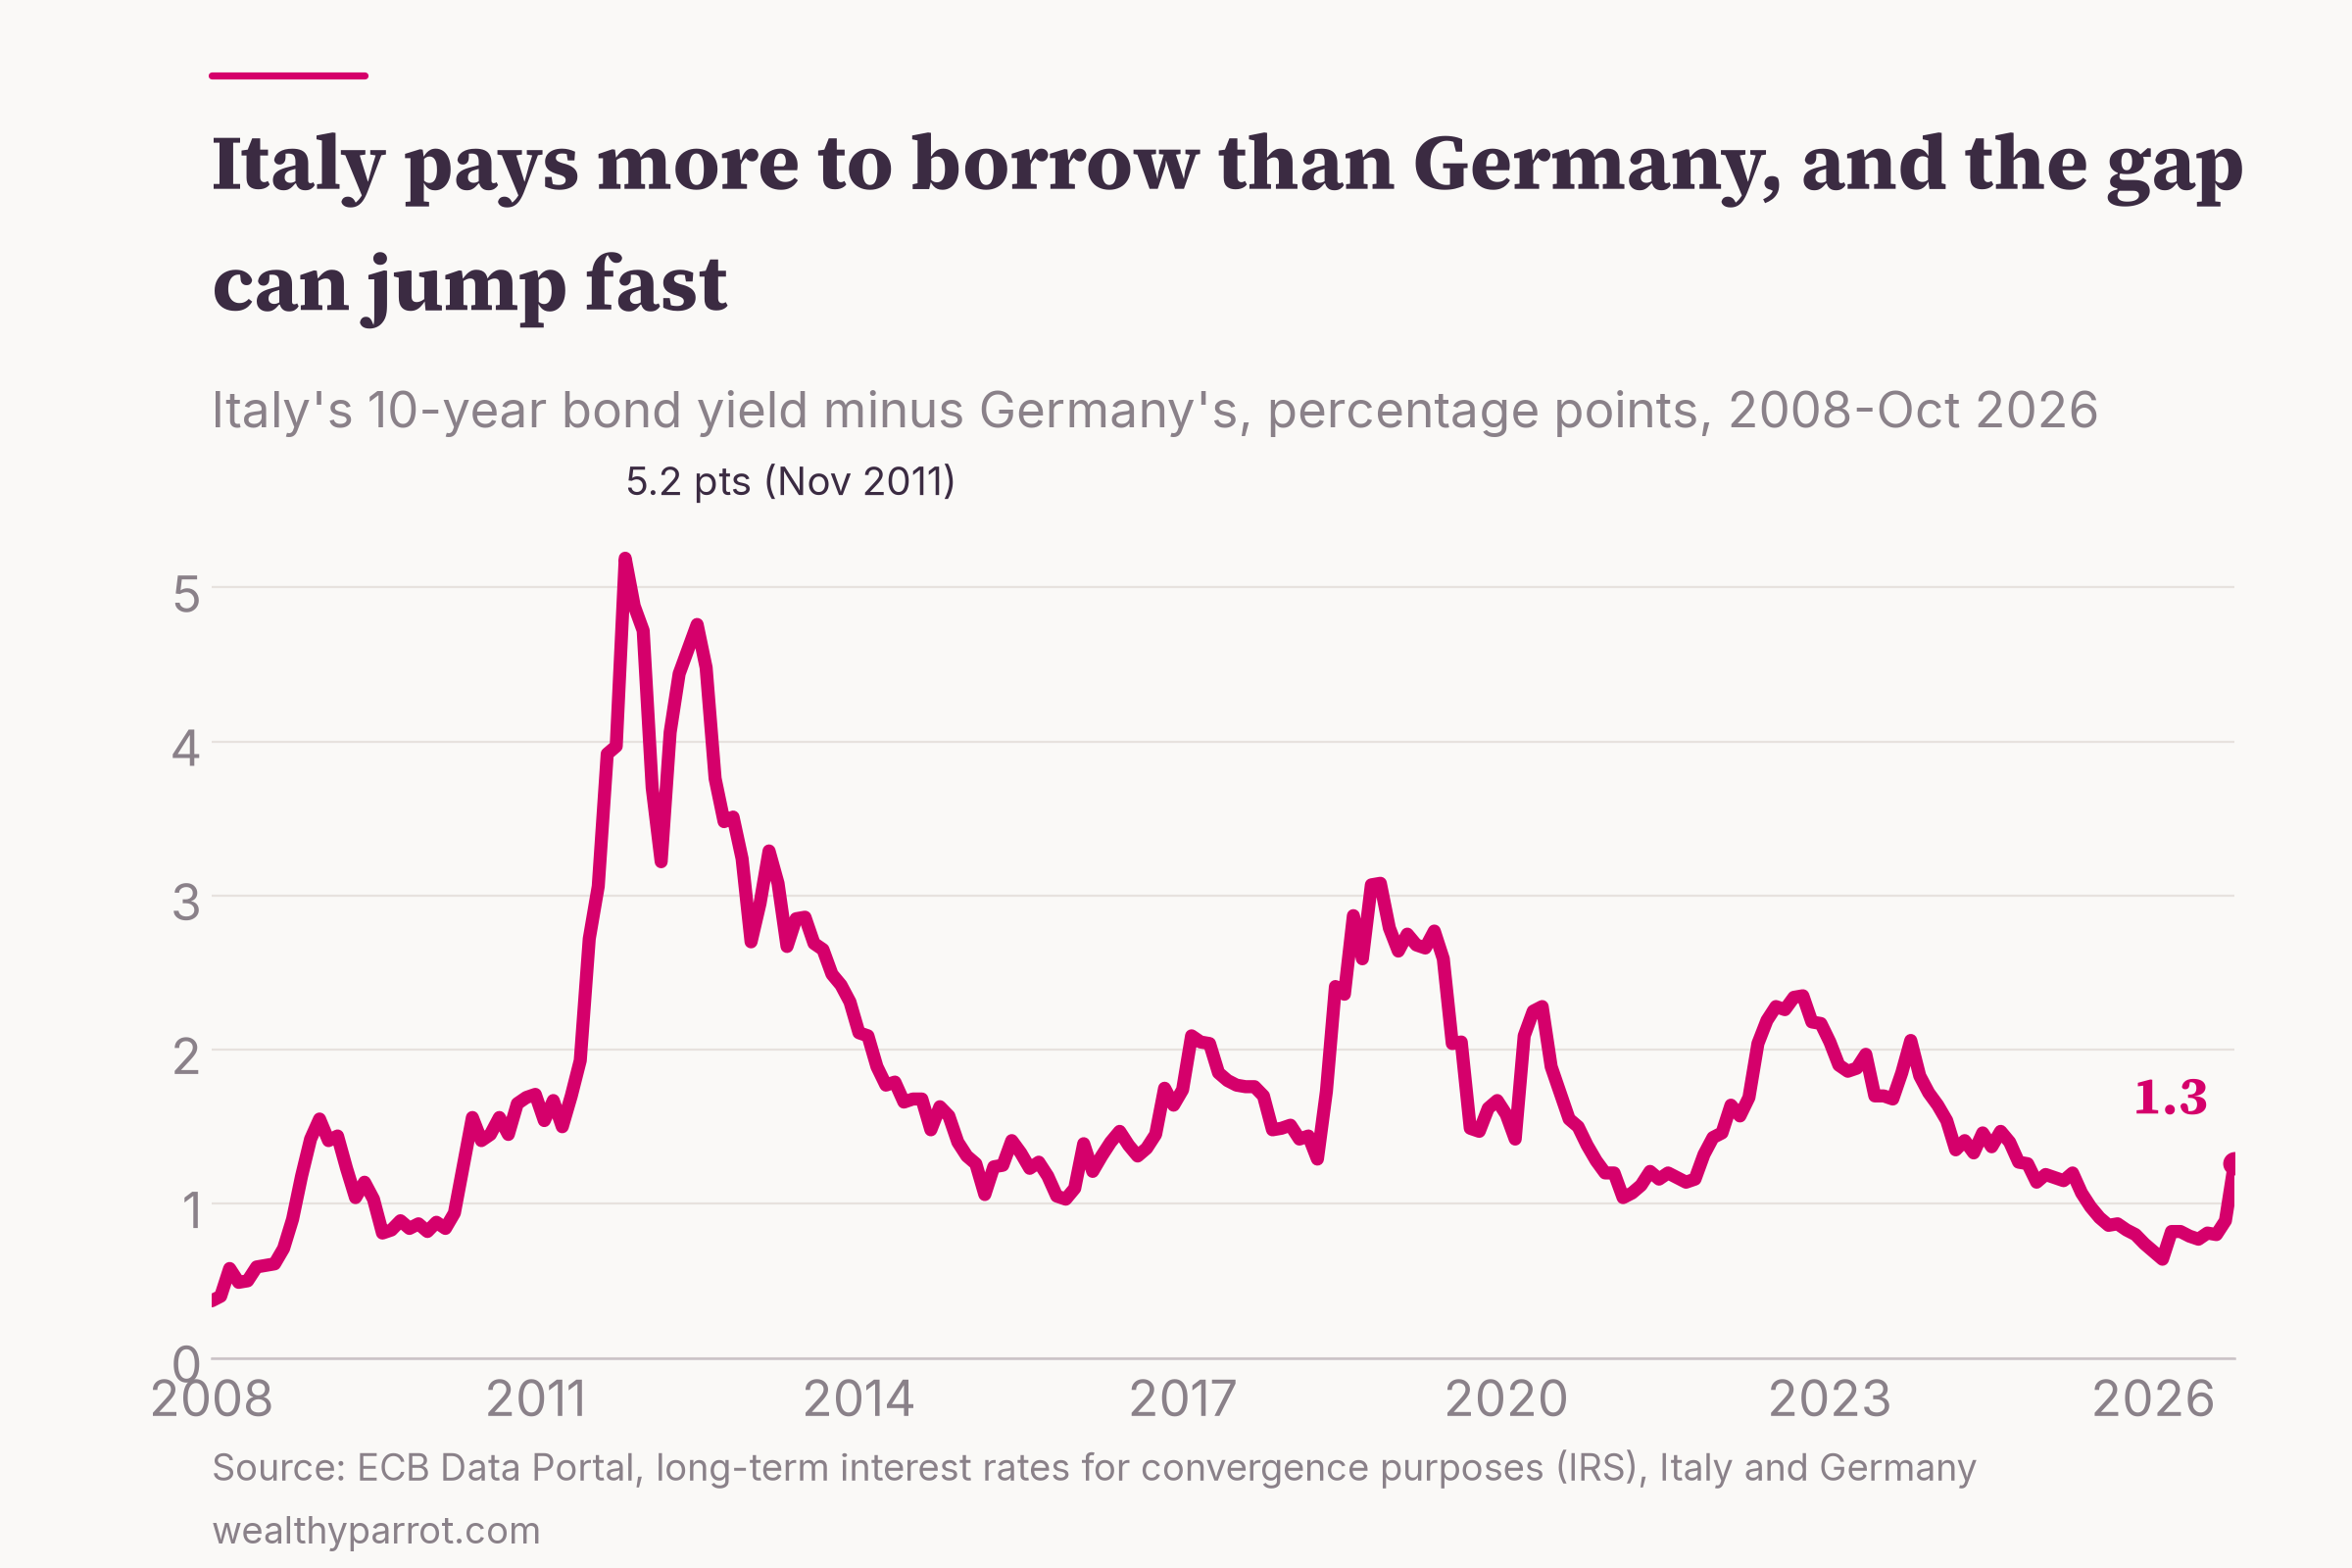
In November 2011, at the worst of the euro debt crisis, that spread hit 5.2 percentage points. Italy was paying over 5 points more per year than Germany to borrow for ten years. That's the fiscal and monetary tug of war at its sharpest. National budgets worried investors, and a single central bank had to decide whether to step in.
Fun fact: in July 2012 the ECB's president, Mario Draghi, said the bank would do "whatever it takes" to preserve the euro. The spread fell from 4.76 points that month to 3.24 by December.
The same fear came back in 2022. As the ECB prepared to raise rates, the Italian spread widened again, from 1.46 points in January 2022 to 2.35 by October. So on 21 July 2022, the same day as its first hike, the ECB announced the Transmission Protection Instrument (TPI). It lets the bank buy a country's bonds to counter what it called "unwarranted, disorderly market dynamics", with no limit set in advance.
As far as I can find in the ECB's announcements, the TPI has never been used. In October 2026 the spread was 1.26 points. A backstop works like a fire extinguisher on the wall. If investors believe it is there and works, it may never be needed.
The fiscal side of Europe is changing too. Germany had a constitutional "debt brake" that limited federal borrowing. On 18 March 2025, the Bundestag voted 512 to 206 to change it, exempting defence spending above 1% of GDP and creating a €500 billion infrastructure fund to be spent over twelve years.
Fun fact: a constitutional change needed a two-thirds majority, at least 489 votes, so the reform passed with 23 votes to spare.
The IMF table above shows the first effect. Germany's deficit is estimated at 4.3% of GDP for 2026, the same as in the Covid year of 2020. For the rest of Europe, the question is what happens when the country with the strongest balance sheet starts borrowing more.
What each lever does to your money
All of this reaches you through three prices. They are what you pay to borrow, what you earn on savings, and what your bonds are worth. Monetary policy moves the first two within months. Fiscal policy works more slowly, through taxes, public services and the amount of government debt in the market.
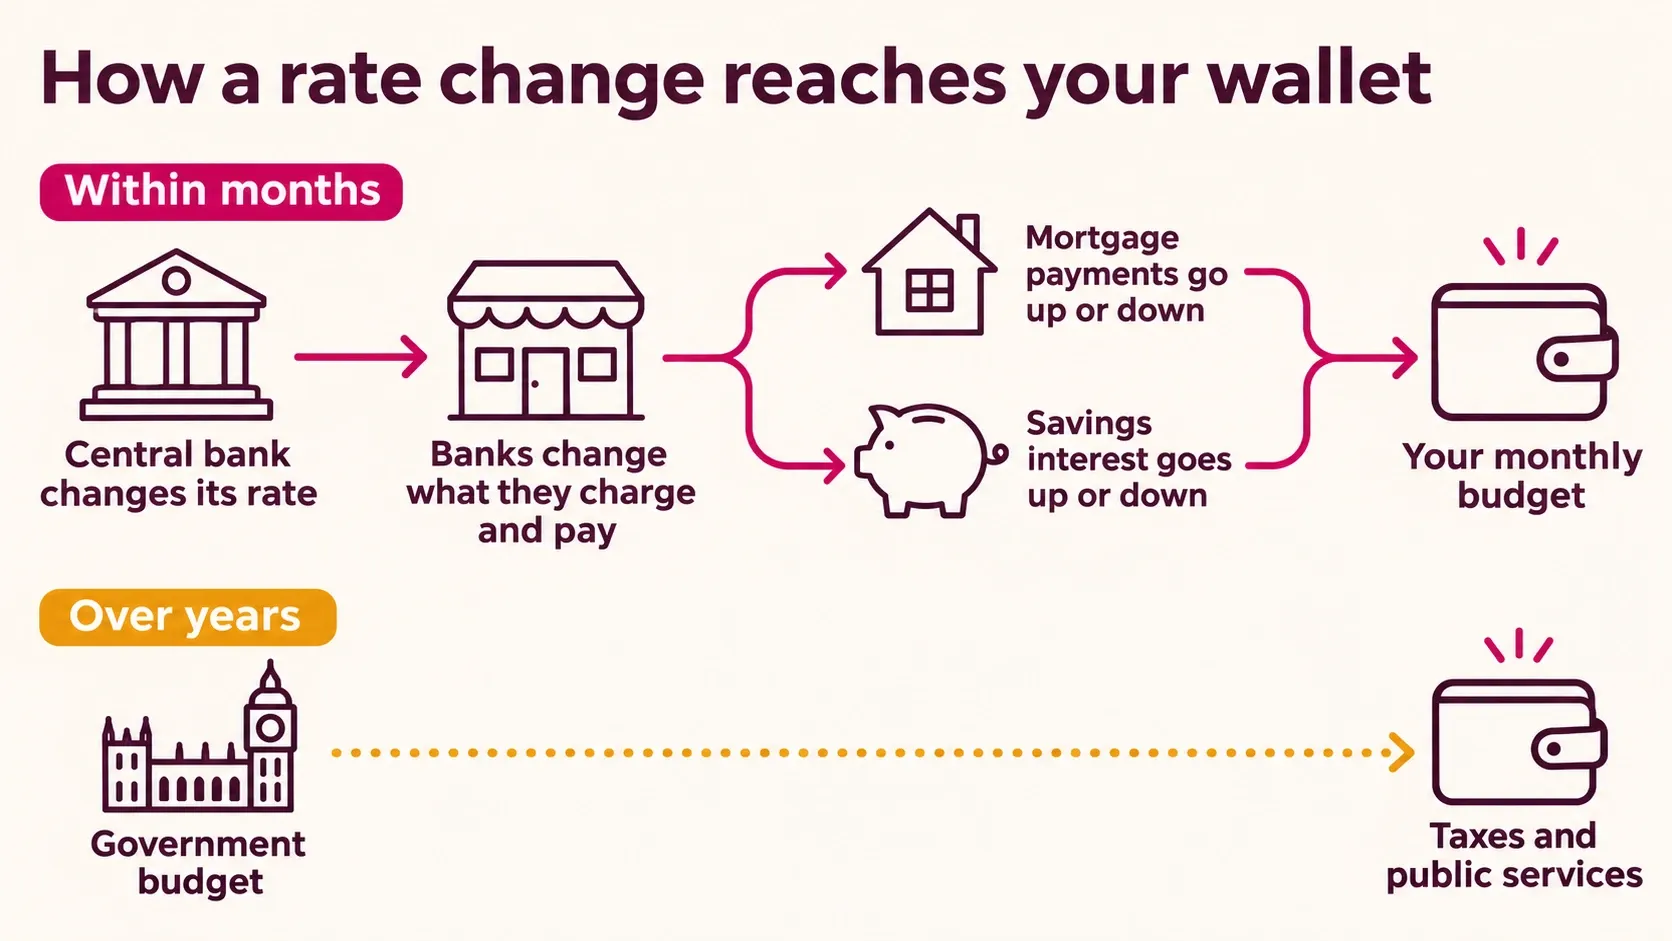
Your mortgage
Take a household borrowing €250,000 over 25 years. According to the ECB's bank interest rate statistics, the average rate on new euro area home loans was 1.31% in December 2021. In November 2023 it was 4.03%.
At 1.31%, the monthly payment is €977.68. At 4.03%, it's €1,323.74. That's €346.06 more each month, or about €4,150 a year, for the same house and the same loan.
Over the full 25 years, total interest is about €43,300 at the lower rate and about €147,100 at the higher one. The gap is more than €100,000 (yes, really, from a rate difference of under three percentage points). In September 2026 the average new mortgage rate was 3.62%, which puts the same loan at €1,267.71 a month.
Do you know whether your own mortgage rate is fixed or variable, and until when? If it's variable, a central bank decision reaches your payment within months. If you locked a fixed rate in 2021, the 2022 hikes didn't touch you, and the ECB's decisions only matter again when you refinance.
Your savings
Ever noticed that your bank was quick to raise its loan rates and slow to raise what it paid on savings? The same statistics show the other side. Households earned an average of 0.15% on deposits fixed for up to a year in December 2021. By November 2023 that had risen to 3.33%.
On €20,000, that's the difference between €30 a year in interest and €666. Higher rates are bad news for borrowers and good news for savers, and many European households are savers first.
Compare that interest with inflation, though. In December 2021, inflation was 5.0%, so a 0.15% deposit lost almost 5% of its buying power that year. In November 2023, at 3.33% interest and 2.4% inflation, savers were finally ahead. In September 2026, deposits paid 2.33% while inflation was 3.8%, so they were behind again.
That's why the size of your emergency fund matters, and why money beyond it usually belongs somewhere else. Cash is safe in euros, though not always in what those euros can buy.
Your bonds
Rising rates hurt existing bonds. If you hold a bond paying 1% and new bonds pay 3%, nobody wants yours at the old price, so its price falls until its yield matches. The longer the bond, the bigger the fall.
That's what made 2022 so painful for bond funds, and I explain the mechanics in my guide to bonds. The flip side is that higher rates mean higher income on the bonds you buy next, which I looked at in why not just buy 30-year bonds at 6%.
Your taxes and public services
Fiscal policy reaches you more slowly. The 2020 deficits were paid with borrowed money, and borrowed money carries interest. When rates were near zero, that interest was cheap. Since 2022, governments rolling over their debt pay more, much like a household whose fixed-rate mortgage comes up for renewal.
That bill has to come from somewhere, whether higher taxes, lower spending elsewhere or more borrowing. I won't predict which mix your own government will choose (nobody I know of has a good record at that). What you can watch is the deficit and the debt level in tables like the IMF one above, because they set how much room a government has the next time a crisis hits.
Your shares
Shares are where fiscal policy shows up most. Government spending lands as revenue somewhere, whether at a construction firm, a defence contractor or a utility. Germany's €500 billion fund will be someone's order book for the next twelve years.
I can't tell you which shares will benefit, and nobody can reliably time it. A broad index fund already owns the companies that will win those contracts, along with the ones that won't.
How to read the next headline
The next time a central bank or a finance ministry makes the news, you can run through a short list of questions.
- Which lever moved? A rate decision comes from the central bank and reaches loans and deposits within months. A budget comes from a government and works through taxes and spending over years.
- Is it pressing or easing? Higher rates and smaller deficits slow an economy; lower rates and bigger deficits speed it up.
- Are the two levers pulling the same way? In 2020 both pushed. In 2022-2023 the ECB braked while many governments still spent.
- What does it change for me? Check whether your mortgage is fixed or variable, what your deposit pays compared with inflation, and how long your bonds are.
- In the euro area, whose budget is it? The ECB sets one rate, but the spread on each country's bonds can move on its own.
If you want the background on how central banks work in detail, I wrote a deep dive on central banks. And for what inflation, deflation and stagflation do to your money, see this explainer.
In October 2022, inflation was at 10.6% and the ECB's rate was at 0.75%. Four years later, the €250,000 mortgage in the example above costs about €290 a month more than at the 2021 rate, and a one-year deposit earns less than inflation again. A rate decision changes those numbers within months, and a budget changes them over years.