How central banks work: who owns them, how they make money, and why the ECB lost billions
How central banks work: what they do, who owns them, how they make money, and why the ECB lost €10.5 billion in 2023-2025. With current ECB and Fed rates.
In 2024 the European Central Bank lost €7.9 billion. The institution that creates euros ended the year short of euros, and it had already lost €1.3 billion the year before. Then it lost another €1.3 billion in 2025.
Nobody was fired, no bailout was arranged, and the euro kept working. Central banks keep accounts like a business, but they aren't one. Why can a central bank lose €10.5 billion in three years and carry on as normal? The answer sits in what a central bank does, who owns it and where its money comes from.
That's the tour. I'll keep the history short, show the numbers, and finish with what any of this means for your savings and your mortgage.
What a central bank is
A central bank is the bank for banks and for the government. You can't open an account at the ECB, but your bank has one, and so does your country's treasury, through its national central bank. When your bank needs cash overnight, or wants somewhere safe to park spare money, it deals with the central bank.
That position gives a central bank three jobs. It issues the currency, it sets the price of borrowing that currency, and it keeps an eye on the banks that lend it to you. Most central banks also run the plumbing that moves money between banks, which is why your instant transfer arrives in seconds.
The euro area adds a twist. One central bank, the ECB, sets rates for every country that uses the euro, while the national central banks (the Bundesbank, the Banque de France, the Banca d'Italia) do much of the hands-on work. Think of the ECB as the head office and the national banks as its branches, each with its own history.
Where central banks came from
The story starts in Sweden. In 1661 a private bank in Stockholm issued Europe's first banknotes, as Clive Gifford recounts in A Quick History of Money.
Fun fact: Europe's first banknotes came from a private Stockholm bank in 1661, seven years before Sweden's parliament founded the Riksbank. Paper money in Europe started as a private experiment, and the state took over the job afterwards.
In 1668 Sweden's parliament set up its own bank, now the Sveriges Riksbank, which calls itself the world's oldest central bank. England followed in 1694. The Bank of England was founded as a private bank to act as banker to the government, and its main purpose was to fund a war against France. It stayed privately owned until 1946, when the government took it over.
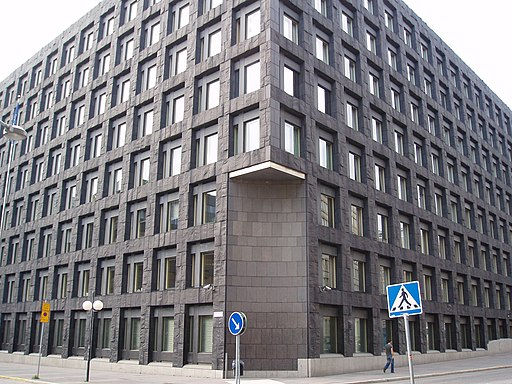
The US was a latecomer. The Federal Reserve Act of 1913 created the Fed, after a run of banking panics. The ECB is the baby of the group (its statute dates from 1 June 1998, months before the euro arrived).
Fun fact: the oldest bank still trading is older than any central bank. Banca Monte dei Paschi di Siena traces its origin to a pawn agency set up by the Republic of Siena on 27 February 1472, to lend to "poor or miserable or needy persons". The bank calls itself "the oldest bank in the world" (its own claim, but a hard one to beat).
The main job: keeping prices stable
Ask the ECB what it is for and price stability comes first. Since its 2021 strategy review it aims for 2% inflation over the medium term. The Fed and the Bank of England use the same 2% number.
Why 2% and not zero? Think of it as a small safety margin. A little inflation leaves room to cut rates in a downturn and keeps the economy away from deflation, where falling prices make people delay spending (I covered that in inflation, deflation and stagflation).
The main lever is an interest rate. When inflation runs hot, the central bank raises rates, borrowing gets more expensive, people and companies spend less, and price rises slow down. When the economy stalls, it cuts.
The catch is timing. The ECB describes the effects as coming with "long, variable and uncertain time lags". A 2024 study of US consumer prices found that after a rate rise, the overall price index only turned significantly lower after more than three years, with big differences between categories. A central bank is steering a supertanker, not a scooter.
How a central bank sets interest rates
Here is the part most explainers skip. A central bank doesn't decree what your bank charges you. It sets the rate it pays or charges banks, and the rest of the market follows.
In the euro area the key number is the deposit facility rate, which is what the ECB pays banks for money they leave with it overnight. No bank will lend to another bank for much less than it can earn risk-free at the ECB, so that rate becomes the floor for the whole money market. Your savings account, your variable mortgage and your company's credit line are all priced from there.
That rate has had a wild decade. The ECB took it below zero in June 2014, down to -0.50% in 2019, and kept it negative for eight years. Yes, banks were paying the central bank to hold their money. Then inflation arrived, and the rate went from -0.50% to 4.00% between July 2022 and September 2023.
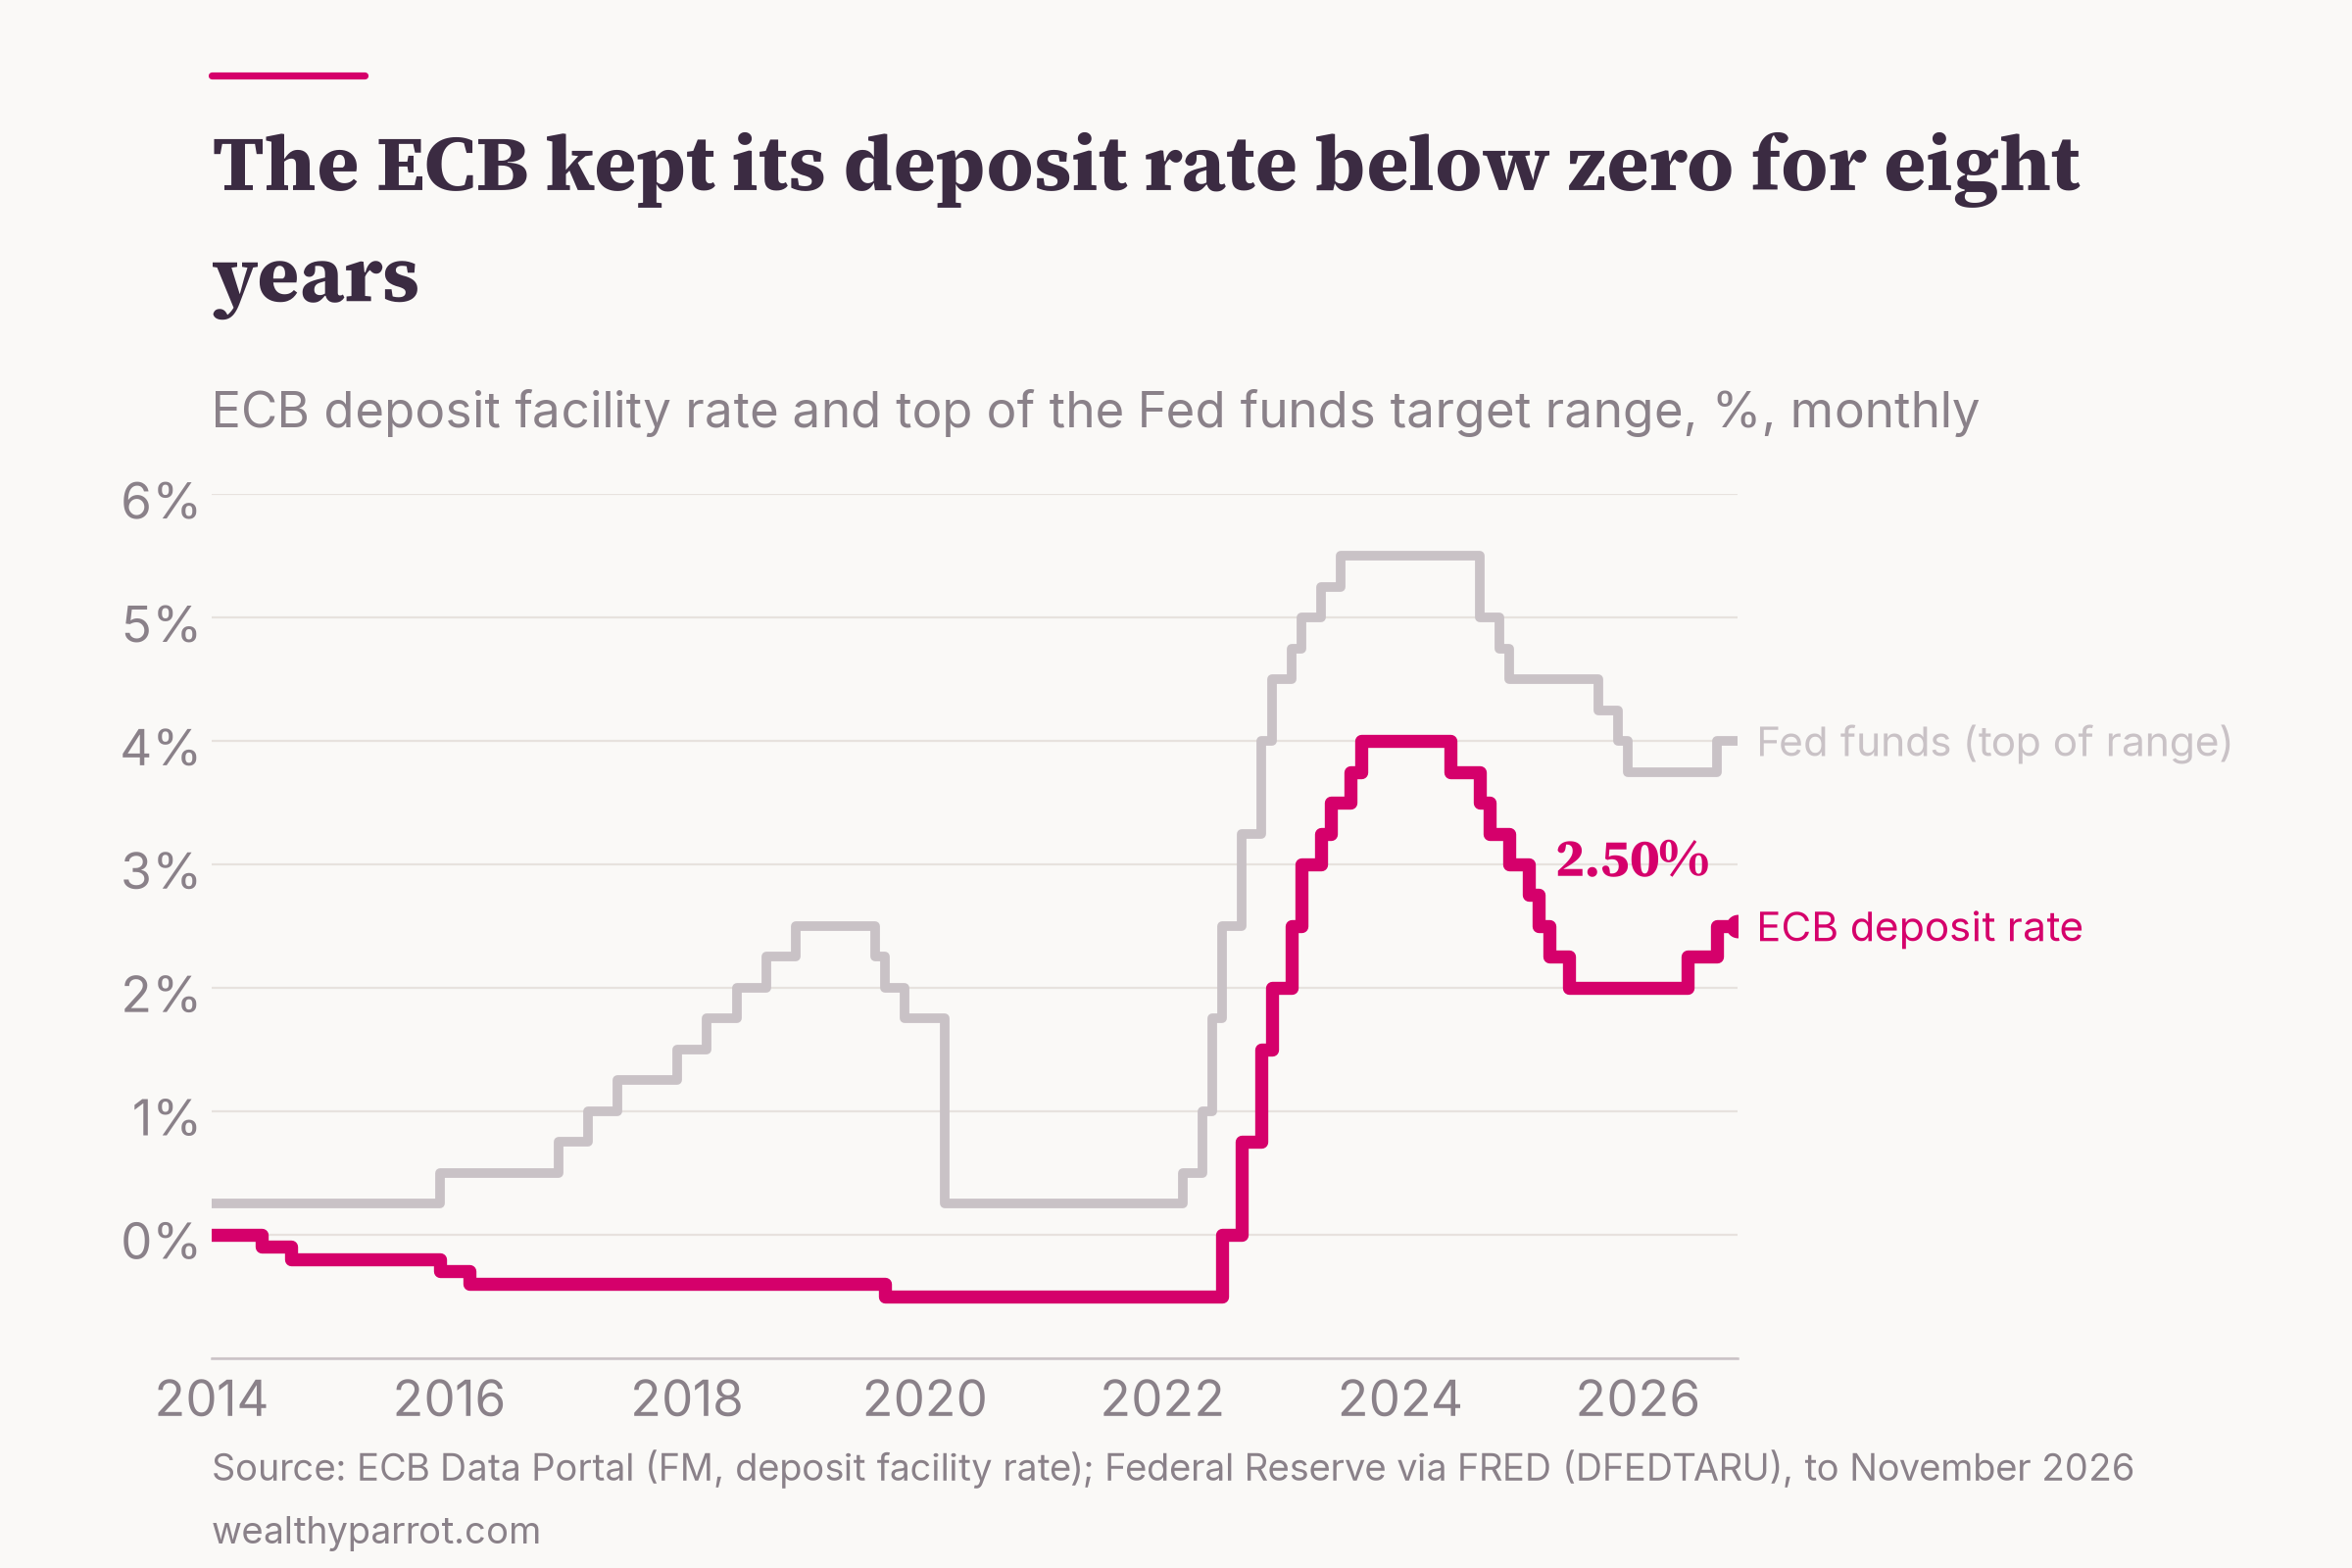
The ECB cut from June 2024 to 2.00% in June 2025, then raised again in June and September 2026, to 2.50%. The Fed's range went from near zero in 2020 to 5.25-5.50% in 2023, and stands at 3.75-4.00% today.
Two tools from the old textbooks deserve a correction. Reserve requirements, the share of deposits a bank must keep at the central bank, are no longer an active lever in either place. The Fed cut them to zero in March 2020. The ECB still has minimum reserves but pays 0% on them.
What does the work today is the rate paid on reserves, which is the deposit rate in Europe and the interest on reserve balances in the US.
Quantitative easing and tightening, done properly
When rates hit zero and the economy still needed help, central banks found a second lever: buying bonds. This is quantitative easing (QE). The central bank creates reserves, uses them to buy government bonds from banks and investors, and pushes long-term interest rates down.
The scale was enormous. The Fed's balance sheet was about $891 billion at the end of 2007. Several rounds of QE took it to about $4.5 trillion by the end of 2014. Covid took it to a peak of almost $9 trillion in April 2022.
Then came the reverse, quantitative tightening (QT). The Fed has let its holdings run down to about $6.8 trillion, and the ECB stopped reinvesting maturing bonds from its main programme in July 2023.
The old article said the ECB started selling bonds, which it didn't. It simply stopped buying replacements when old bonds were repaid, so the pile shrinks as they mature.
How a central bank makes money
Picture the simplest possible bank. It borrows at 0% and lends at 3%. That's a nice business, and for most of its history it is what a central bank looked like.
Its cheapest funding is the cash in your wallet. A banknote is a liability of the central bank that pays no interest at all. The central bank uses that free funding to hold bonds and other assets that do pay interest. The difference is called seigniorage, and it is the oldest profit engine in finance.
QE made the engine bigger for a while. The Fed paid banks almost nothing on their reserves while collecting interest on trillions of dollars of bonds. In 2021 it sent $107.4 billion to the US Treasury, and Blanchard and Summers note in Evolution or Revolution? that it had remitted more than $650 billion since 2009.
Those profits don't stay with the central bank. After costs, the Fed sends them to the US Treasury, and the ECB sends them to the national central banks, which pass most of theirs on to finance ministries. A profitable central bank quietly lowers the tax bill.
Why the ECB lost €10.5 billion
Now flip the picture. QE left central banks holding long-term bonds bought when yields were close to zero. Those bonds keep paying their old, low, fixed coupons. On the other side, the reserves created to buy them pay the current policy rate, which reset almost overnight.
So when the ECB took its deposit rate from -0.50% to 4.00%, it suddenly owed banks interest on the reserves it had created, while its bonds kept paying what they paid in 2020. Its press release on the 2025 accounts spells out that mismatch, with liabilities at variable rates and assets at fixed rates and long maturities.
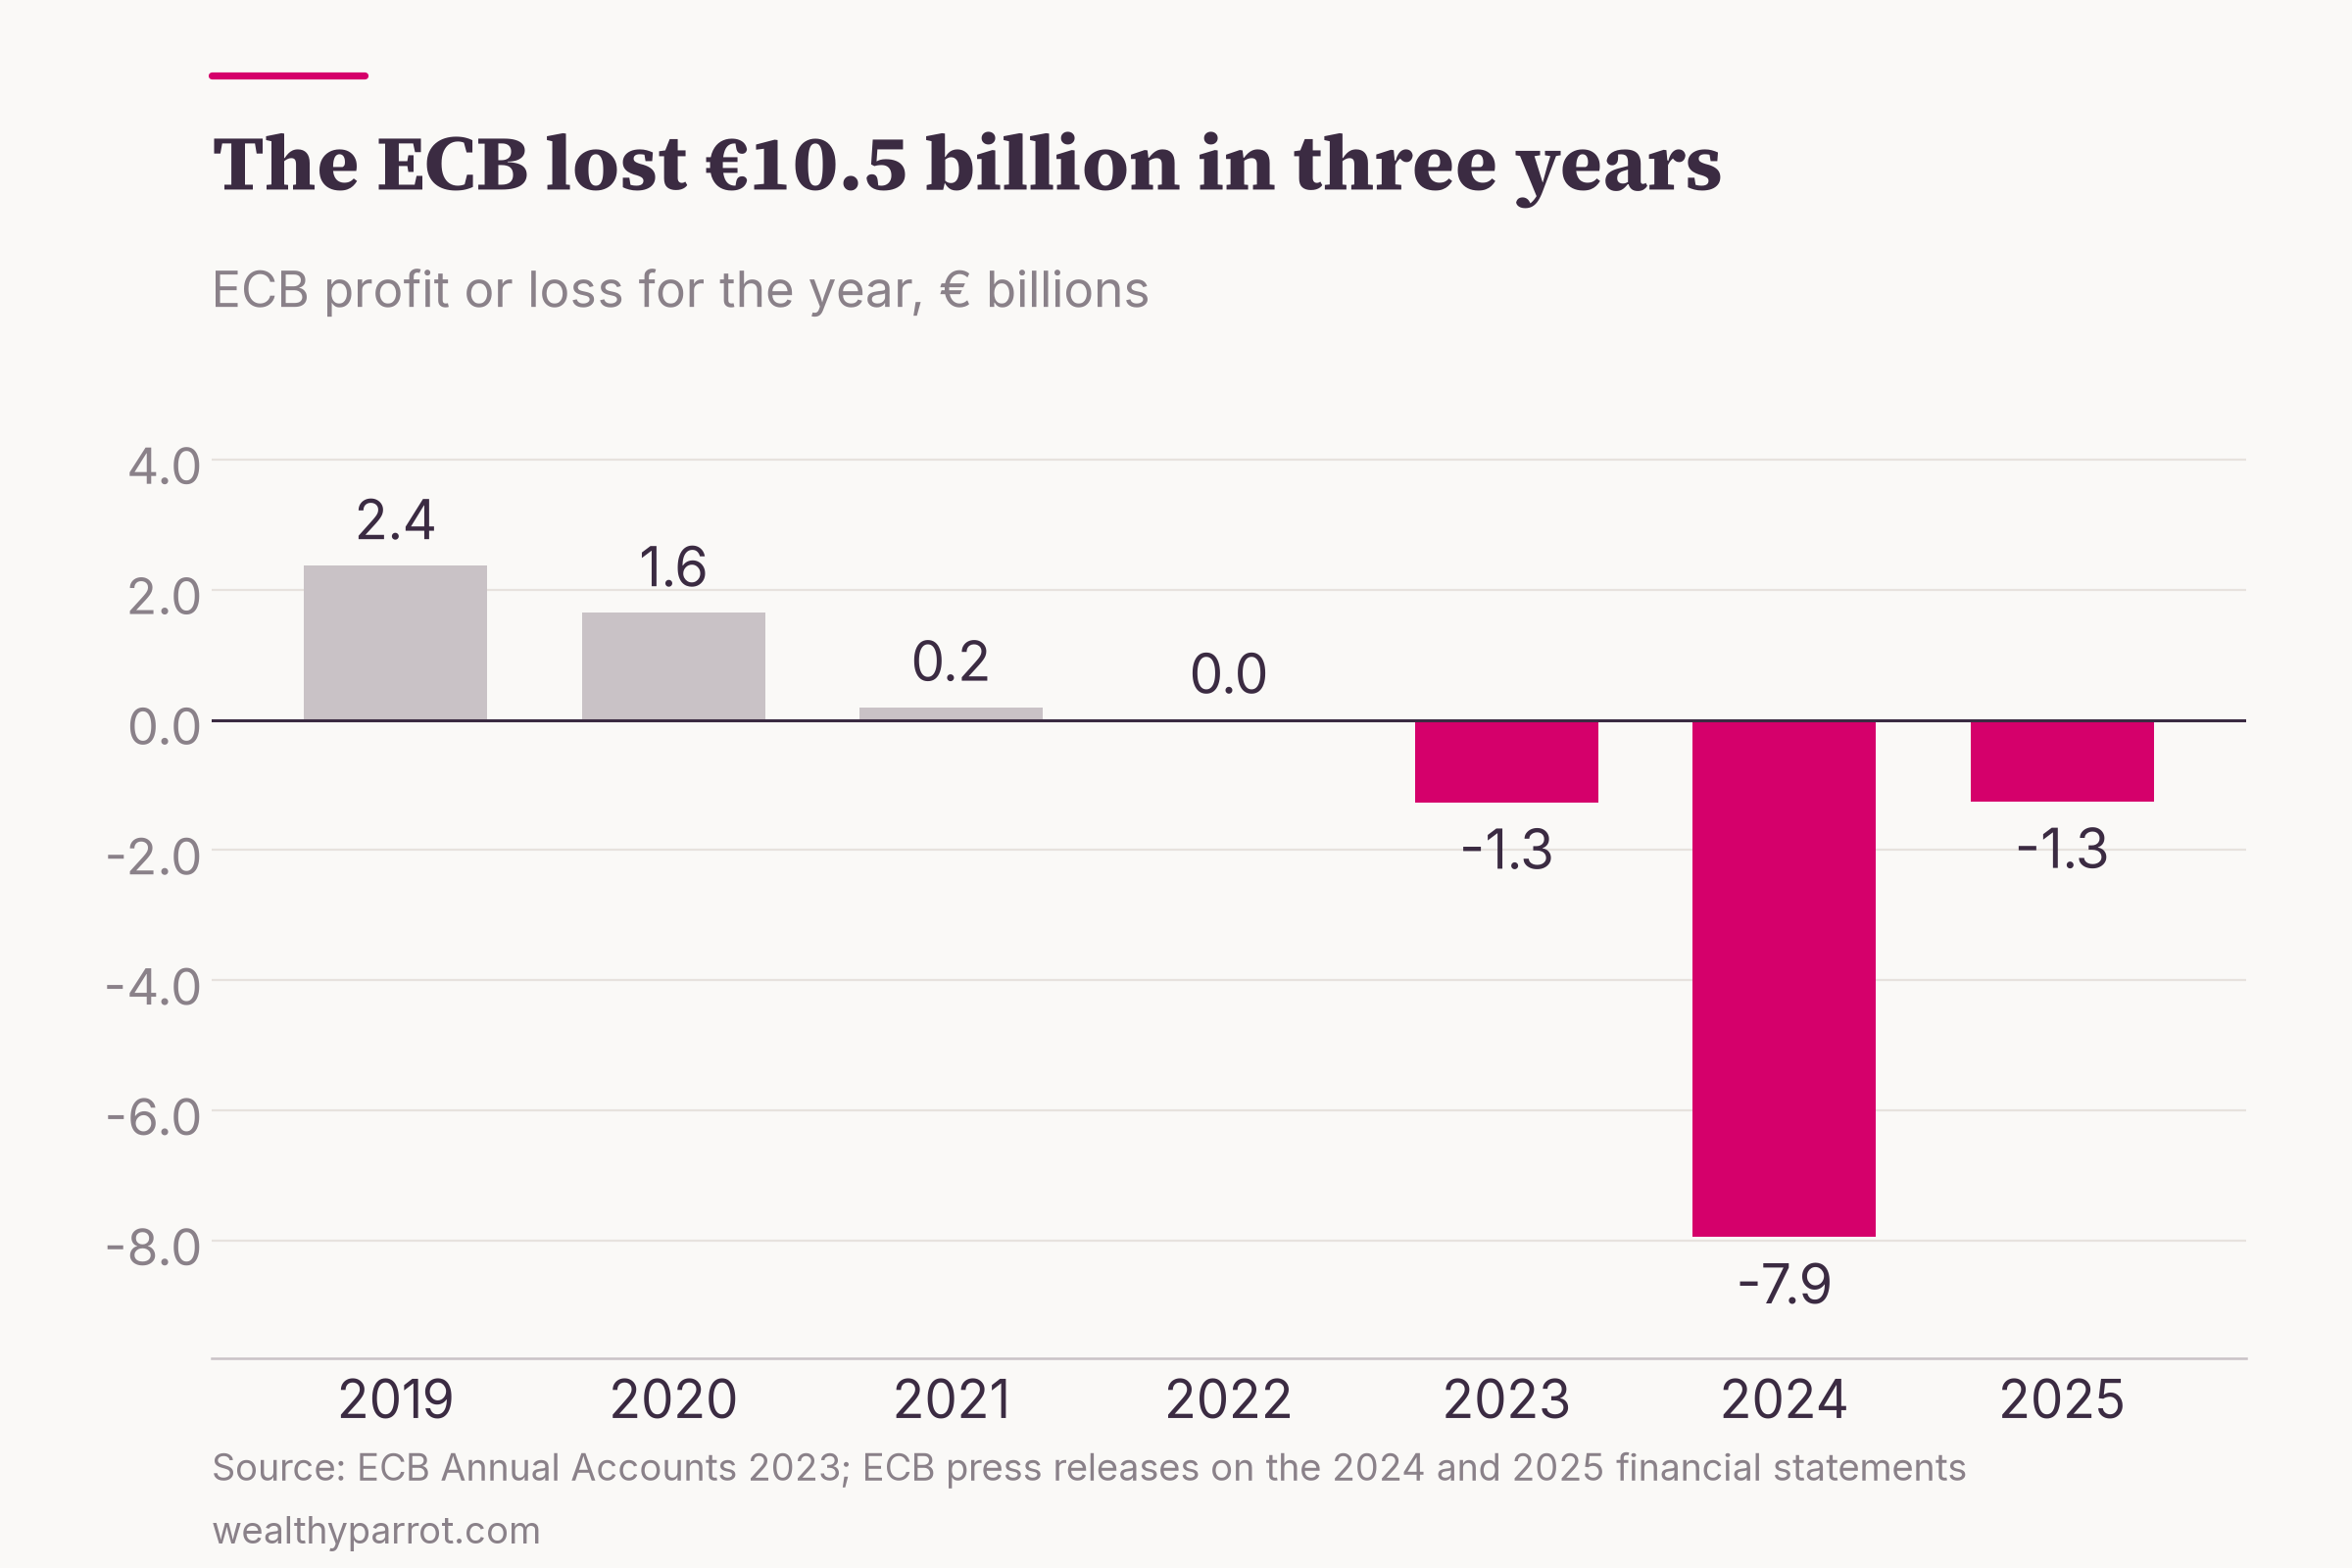
The result is on the chart. The ECB made €2.4 billion in 2019, broke even in 2022, then lost €1.3 billion, €7.9 billion and €1.3 billion. It had already used up its €6.6 billion provision for financial risks to soften the 2023 result.
Fun fact: the ECB's 2024 loss of €7.9 billion was equal to about 73% of its subscribed capital of €10.8 billion. A commercial bank in that position would be talking to its supervisor. The ECB just carried the loss forward.
The losses stay on the balance sheet, to be offset against future profits, and there is no profit distribution to the national central banks until then. The ECB expects to return to profit in 2026 or the year after. It also points out that its capital and revaluation accounts (unrealised gains on gold and other holdings) added up to €71 billion at the end of 2025.
The Fed tells the same story in different accounting. Instead of booking a loss, it records a "deferred asset": the profits it must earn back before it sends money to the Treasury again. That hole reached about $246 billion in January 2026 and was about $231 billion in November 2026, shrinking slowly as the Fed earns again.
Why doesn't any of this break the system? Because a central bank can't run out of its own currency, and it doesn't need profits to do its job. As the ECB puts it, it can fulfil its mandate "regardless of any losses" (yes, really).
The cost lands elsewhere. Governments miss out on years of dividends they used to count on, so QE sends its fiscal bill late.
Who owns a central bank?
The answer varies more than you'd guess.
The ECB is owned by the national central banks of all EU countries, which subscribed its €10.8 billion of capital. The two biggest shareholders are the Bundesbank, with 21.77%, and the Banque de France, with 16.36%.
The Fed's own FAQ says it is "not owned by anyone". Commercial banks that join the system must hold stock in their regional Reserve Bank. That stock doesn't work like a share in a company, since it carries a legally required dividend and no claim on the profits, which go to the Treasury.
The Bank of England has belonged to the government since 1946. And then there's Switzerland.
Fun fact: you can buy shares in the Swiss National Bank. Its 100,000 registered shares are listed on SIX Swiss Exchange, but the dividend is capped by law at 6% of the CHF 250 nominal value, or CHF 15 a share. The SNB says the share price usually moves like a long-term government bond with a 6% coupon.
Ownership matters less than independence. A central bank that a government can order to print money for its spending stops being much use. That's why rich countries tend to give theirs a clear mandate and keep politicians away from the rate decision.
Fun fact: central banks have a bank of their own. The Bank for International Settlements in Basel was set up in 1930 and is owned by 63 central banks, from countries that account for about 95% of world GDP.
Keeping the banks safe
The second big job is supervision, which means making sure the banks holding your deposits can survive a bad year. The ECB supervises the largest euro-area banks directly. A bank counts as significant if, among other tests, its assets exceed €30 billion.
The US draws the line much higher. In 2018 Congress raised the threshold for the strictest rules from $50 billion of assets to $250 billion. Silicon Valley Bank had about $212 billion of assets when it was closed on 10 March 2023, after tripling in size between 2019 and 2021. The Fed's own review concluded that the 2019 tailoring of the rules had lowered its capital and liquidity requirements (spoiler: the bank sat below the strictest line).
At the top of the pyramid sit the banks whose failure would shake the world. The Financial Stability Board's 2025 list names 29 of them, sorted into buckets that set how much extra capital each must hold. JPMorgan Chase sits alone in the top occupied bucket. Bank of America and China's ICBC moved up a bucket and Deutsche Bank moved down, with the new requirements taking effect from January 2027.
Digital money
Central banks have spent the last few years asking whether they should issue digital cash themselves: a central bank digital currency, or CBDC. In the latest survey by the BIS, 85 of 93 central banks, or 91%, were exploring one at the end of 2024.
Europe is furthest along among rich economies. In October 2025 the ECB moved the digital euro to its next phase. If EU legislation is in place during 2026, a pilot could start in 2027 and a first issuance could come during 2029. The ECB estimates development costs of about €1.3 billion, and running costs of about €320 million a year after that.
China went first and then changed course. The PBOC reported 3.48 billion digital yuan transactions worth 16.7 trillion yuan by the end of November 2025. From January 2026, digital yuan held in bank wallets counts as a bank deposit and earns interest, which makes it look less like digital cash and more like a digital bank account.
And Bitcoin? El Salvador made it legal tender in 2021. As part of an IMF programme in 2025, it made accepting Bitcoin voluntary for businesses and confirmed that taxes are paid only in US dollars. I covered the crypto side in more depth in my piece on blockchain and traditional finance.
Climate: a mandate fight
Climate risk was the fashionable new topic for central banks a few years ago, and it has become a test of how far their mandate stretches. The ECB still treats climate change as part of its work. The Fed went the other way. In January 2025 it withdrew from the NGFS, the central banks' climate network, saying the network's work had moved outside the Fed's statutory mandate.
The disagreement is less about the weather than about the same question as the losses: what a central bank is for, and who gets to decide.
What central banks mean for your money
You'll never hold an account at the ECB, but its decisions still reach you:
- Savings: the deposit rate sets the floor for what your bank pays you. With the ECB at 2.50%, a current account paying nothing means your bank keeps the whole spread, so shop around.
- Mortgages: variable rates follow the policy rate closely. Fixed rates follow long-term bond yields, which move on what markets expect the central bank to do next.
- Bonds: prices fall when rates rise. If you own bond funds, a hiking cycle shows up as a loss before it shows up as better income (more in why not just buy 30-year bonds at 6%?).
- Headlines about central bank losses: they're real, but they aren't a crisis. They mean governments get smaller dividends for a few years, which is a cost to taxpayers rather than to depositors.
For how rate decisions and government budgets pull together (or against each other), read my comparison of fiscal and monetary policy, which covers what each lever does to your mortgage, savings, bonds and shares. And if you want to read a central bank's accounts yourself, the same tools apply as for a company: start with my guide to reading a balance sheet.
The ECB lost €10.5 billion and kept doing its job. Its real asset was never its capital. It was the trust that a euro will still buy roughly what it bought last year, minus about 2%.