The psychology of saving: why we spend more than we should - Part I

Do you ever feel like your wallet has a leak? You mean to put money aside for that dream holiday, or for not eating cat food in retirement, and somehow it vanishes faster than free donuts in the office kitchen. It's like knowing vegetables are good for you and still reaching for the pizza. You are not alone (yes, even people who read personal finance blogs), and it's probably not a maths problem.
Look at the numbers. American households saved 3.8% of their disposable income in September 2026, and in a May 2025 survey 24% of US adults said they had no emergency savings at all. Euro area households look far thriftier, putting aside 14.2% of their income in the second quarter of 2026 (Eurostat measures it gross, the BEA net, so the gap is smaller than it looks). But a national average tells you nothing about your own bank account at the end of the month.
So why is saving so hard, even for people who earn well and know the theory? Mostly because the brain doing the saving was built for a world without payslips, card terminals and one-click checkouts. This part covers the six mental shortcuts that make us spend more than we planned, with one counter-move for each. Part II covers the outside triggers (social pressure, how we pay) and the full saving system.
Your brain on money
For decades, traditional economics assumed we are all rational robots, always choosing whatever maximises our long-term happiness (economists call it "utility"). Be honest. When did you last make a money decision purely on logic (and no, the spreadsheet you built to justify the new bike doesn't count)?
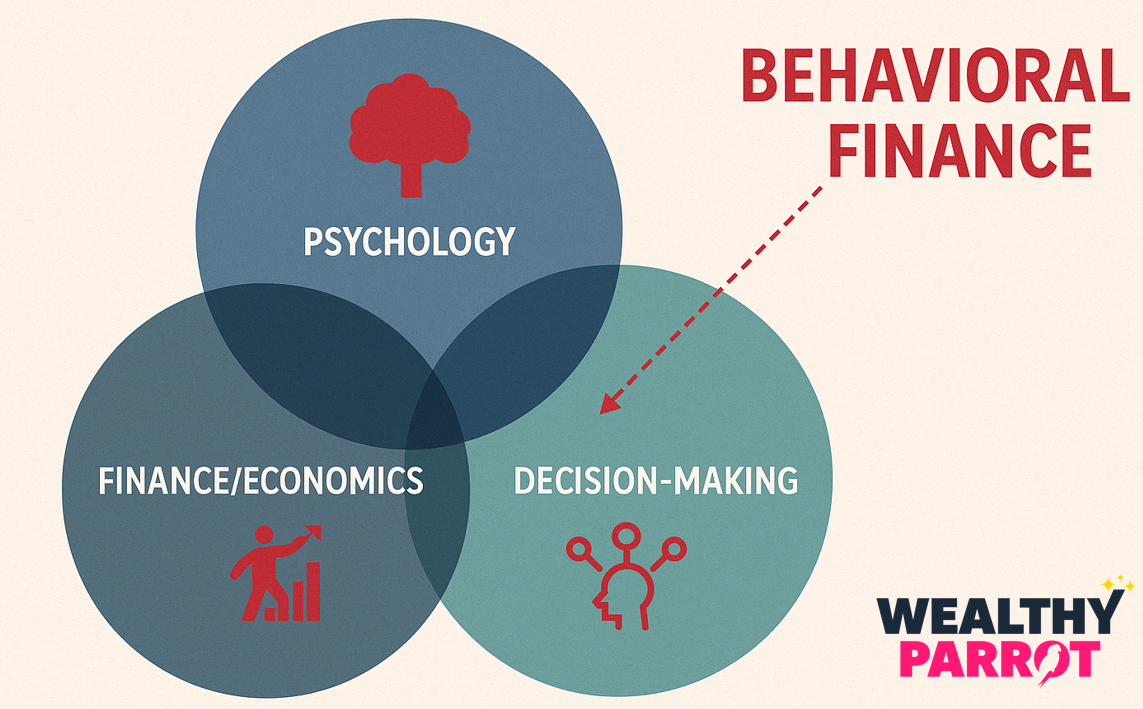
Behavioral finance is what you get when psychology and economics share a desk. It starts from what people actually do with money, rather than what a perfect calculator would do. Emotions like fear and greed, limited attention, social pressure and a handful of predictable thinking errors all push our choices around.
This matters most for small, frequent decisions. You choose whether to invest your pension a few times in your life. You choose between the fancy coffee and the packed lunch every single day, and that's where the leak usually is.
Most of the errors come from heuristics, the mental shortcuts the brain uses to decide fast. They are brilliant when you're dodging a cyclist and much less helpful when you're deciding whether to splurge or save. Each one below bends how we see value, risk or time, and almost always in the same direction: towards the shiny thing now instead of the bigger pot later.
Present bias: the "I want it now" problem
Present bias is our inner toddler screaming for one treat right now instead of two treats later. We give a reward we can have immediately much more weight than the same reward next month, and we treat future-us as a stranger who can deal with the consequences.
The odd part is how inconsistent it is. Offered €100 today or €110 tomorrow, plenty of people take the €100. Offered €100 in 30 days or €110 in 31 days, almost everyone waits the extra day for the €110.
It's the same one-day wait for the same €10, but when "now" is on the table, our patience collapses. Economists call this pattern hyperbolic discounting. We are impatient about short delays that start today, and patient about the same delays far in the future.
Saving runs straight into it. Spending gives you a small hit of pleasure at the till. Saving gives you a vague feeling of security decades away, for a future self you can barely picture. Retirement planning makes it worse, because the long, uncertain calculation is tiring, and the brain gives up and buys the nice coffee machine instead.
You have probably heard the Marshmallow Test used as proof that patient children become successful adults. The story is shakier than the legend.
When researchers re-ran the study in 2018 with a larger and more varied sample, the link between waiting for the second marshmallow and later school results was half the size of the original. Once they accounted for family background and early ability, it shrank by another two thirds.
Willpower matters less than the legend says, and circumstances matter more. That's good news for savers, because circumstances are easier to change than character.
Fun fact: in the 2018 replication, most of the difference in later results came from whether a four-year-old could wait at least 20 seconds. Holding out for the full seven minutes added little.
The counter-move is to stop relying on willpower and take the decision away from present-you. Move savings out on payday, automatically, before you see the money.
The best-known version is the Save More Tomorrow plan. Employees agreed in advance to save part of each future pay rise. The future rises cost nothing today, so present bias barely objected. Average saving rates went from 3.5% to 13.6% in about 40 months.
Loss aversion: why saving feels like losing
Loss aversion means a loss hurts more than an equal gain feels good. Daniel Kahneman and Amos Tversky estimated that losses weigh roughly twice as much as gains. Losing €50 ruins your afternoon; finding €50 is merely nice.
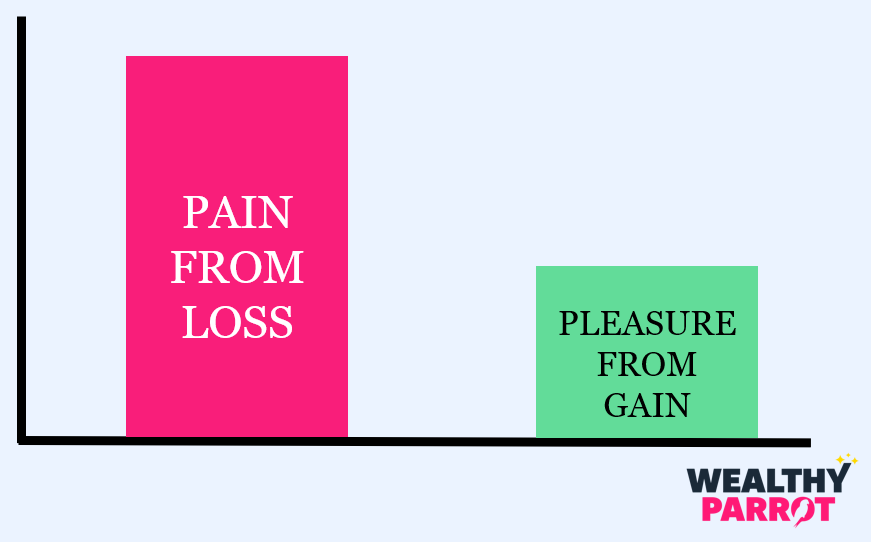
It shows up even where experience and big money should iron it out. Two Wharton economists studied more than 1.6 million putts on the PGA Tour. Professional golfers sank putts for par (avoiding a "loss" against the hole's par score) more often than birdie putts from the same distance (a "gain"), by 2 to 3 percentage points. Tiger Woods included (so if you feel silly about your own biases, you're in good company).
The authors estimated the bias cost the best players more than $1.2 million a year in prize money.
For savers it does three things. First, it makes us play too safe. Fear of seeing the balance dip keeps money in a current account that loses value to inflation every year, which is a slow loss nobody notices because no number turns red.
Second, saving itself can feel like a loss. Each euro moved to savings is a euro of fun you "lose" today, and that sting is vivid while the future benefit is abstract. The same wiring makes cutting back very hard when income falls, because a lower lifestyle feels like losing something you already owned.
Third, it creates the disposition effect, which is finance-speak for holding losing investments too long and selling winners too early. In a study of 10,000 brokerage accounts, investors were about 50% more likely to sell a share that was up than one that was down. Selling the loser would mean admitting the loss, so people cling to it like Gollum to his Precious, and the losers they kept went on to do worse than the winners they sold.
Fun fact: the same accounts showed the pattern flipping in December, when investors finally sold losers to cut their tax bill. A tax deadline was enough to overrule the brain.
The counter-move is to save from money you have not got used to yet. Raise your automatic saving on the day a pay rise lands, before the extra money becomes part of your lifestyle, and nothing feels taken away. For investments, ask "would I buy this today at this price?" instead of "how much am I down?"
Anchoring: stuck on the first number
Anchoring is the habit of leaning heavily on the first number we see.
Picture two identical laptops at €1,400. One just says €1,400. The other has €1,900 crossed out and €1,400 written next to it. The second one feels like a bargain, although the price you'd pay is the same.
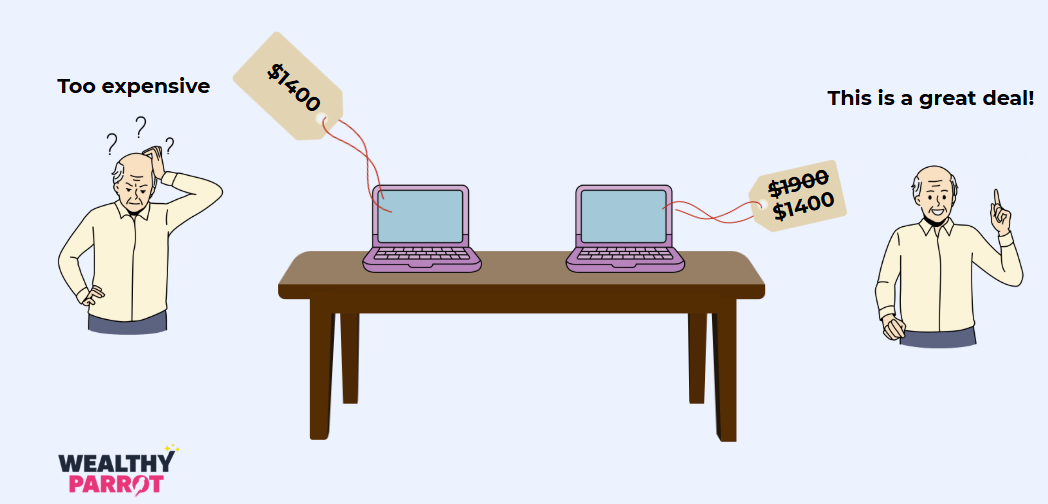
The first number becomes the starting point, and we adjust away from it, but never enough. That's why the car dealer walks you past the fully loaded €60,000 model before showing you the €45,000 one, and why the "was" price on a sale tag is there at all. It works even when the anchor is obviously random.
Fun fact: in a classic 1974 experiment, Tversky and Kahneman spun a wheel of fortune rigged to stop at 10 or 65. They then asked people what percentage of United Nations members were African countries. The median guess was 25% among people who saw 10, and 45% among people who saw 65.
Anchors work on our own budgets too. That beach house you rented for €180 a night five years ago now costs €300, and your brain shouts "rip-off" even if €300 is today's going rate. A share bought at €50 that has fallen to €20 gets held "until it's back to €50", as if the market knew or cared what you paid.
The most expensive anchor is your own spending. Every pay rise lifts your spending a little, and the new level quickly becomes the reference point. Saving the next bonus then feels like a cut, and the lifestyle inflation trap closes.
The counter-move is to set your number before you see theirs. Decide what a laptop, a car or a holiday is worth to you before you open the shop page, and write your budget down before the negotiation starts. For your own spending, anchor on a saving rate (say, 15% of every pay rise) rather than on last year's lifestyle.
Mental accounting: different piles of cash
Meet Bob. He gets €100 for working a long, hard week, and decides it must go to savings. He then gets €100 he didn't expect, and books dinner at the new five-star restaurant.
Same €100, completely different fate. That's mental accounting. We sort money into imaginary jars by where it came from and what it's "for", even though money is fungible (any euro can do the job of any other euro).
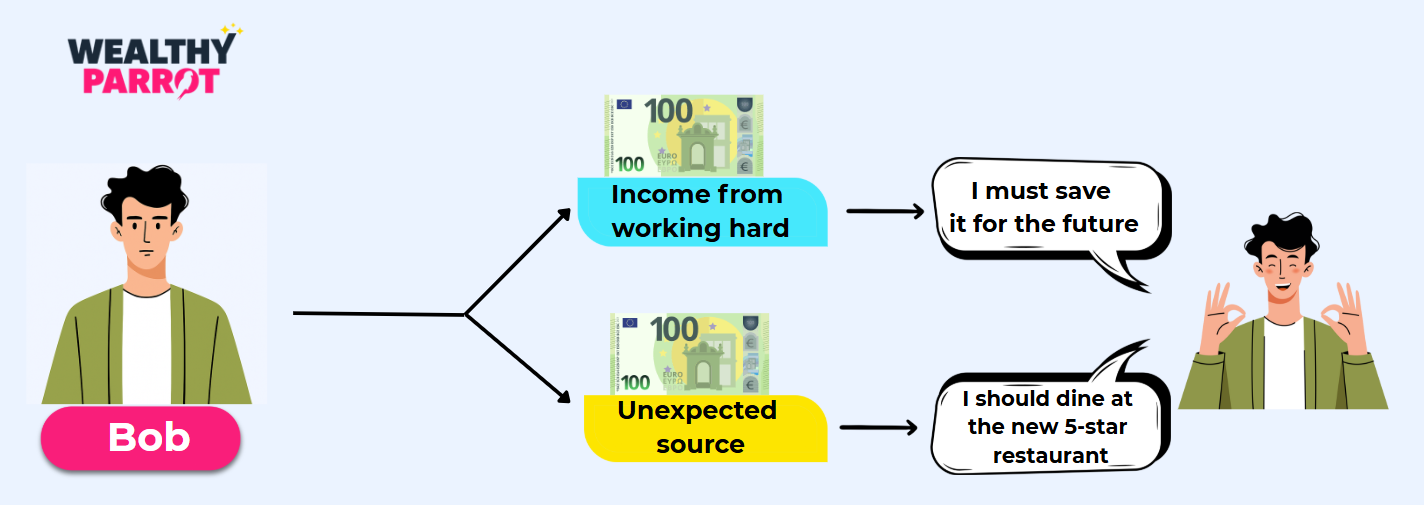
The jars cause real damage. A common one is keeping savings in an account earning, say, 2% while carrying a credit card or overdraft balance charging 20%. Logically you would pay off the debt. But the money sits in the "savings" jar, so it can't touch a "debt" problem, and the gap between the two rates leaks out every month.
Windfalls get the same treatment. Tax refunds, bonuses and birthday money feel like "house money", like casino winnings, so we spend them more freely than salary. Apps and games exploit it too. Spending 1,000 "gems" feels softer than spending €10, even when they are the same thing.
Fun fact: Richard Thaler, who gave mental accounting its name, won the 2017 Nobel prize in economics for his work in behavioural economics, of which mental accounting is one of the best-known pieces.
Mental accounting is the one bias here you can turn into a tool. If your brain wants jars, give it jars with a purpose. Separate accounts or sinking funds for "emergency fund", "holiday" and "new laptop" make each goal concrete and harder to raid. That's the idea behind Kakeibo, the Japanese budgeting method, and behind sizing your emergency fund as its own pot.
The counter-move is to label your jars on purpose, and send every windfall to one of them before it lands in your current account. A simple rule is to send half of any windfall to a goal jar and keep half to enjoy (guilt-free, that's the point).
Hedonic adaptation: the shine wears off
Remember the thrill of a new phone, a new car or a pay rise? A few months later it's just your phone, your car, your salary. Psychologists call this hedonic adaptation, or the hedonic treadmill. We get used to good things quickly, and our happiness drifts back towards its usual level.
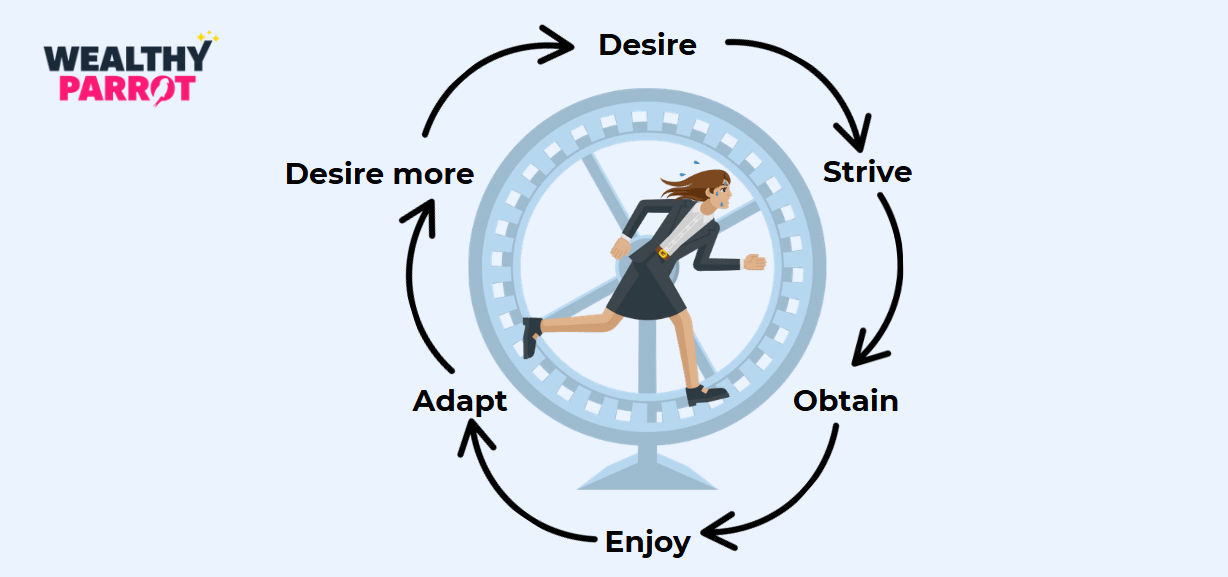
On the treadmill, every purchase gives a boost that fades, so we look for the next one. Yesterday's luxury becomes today's normal. Once you're used to two streaming services and a weekly takeaway, cutting them feels like deprivation rather than a return to last year.
The best-known example used to be lottery winners, who supposedly end up no happier than before. That claim comes from a small 1978 study.
A much larger study of Swedish lottery players, surveyed 5 to 22 years after their win, found that big winners were more satisfied with their lives for over a decade, with no sign of fading. The effect on day-to-day happiness was smaller, and it ran mostly through satisfaction with their finances.
In other words, we adapt to the stuff, but the security of having money in the bank keeps paying off.
Social comparison speeds the treadmill up. You adapt to your new car, then see a friend's newer one, and yours suddenly feels shabby. The reference point is no longer your old life; it's everyone else's highlight reel. I wrote about how these patterns keep running even after people reach their savings goals in the hardest part of FIRE.
The counter-move is to use adaptation in your favour. Put a waiting period on non-essential purchases (a week for small ones, a month for big ones) and let the desire fade before the money goes. And since the Swedish data says financial security is the part of a windfall that lasts, treat savings as something you are buying, not something you are giving up.
Five more biases that empty your wallet
Overconfidence makes us sure we'll earn more next year, save more "later" and have our spending under control. It's the reason so many plans to save start next month. If your saving plan has started "next month" three months running, that's overconfidence talking (I've been there). Plan on this year's income, not next year's hopes.
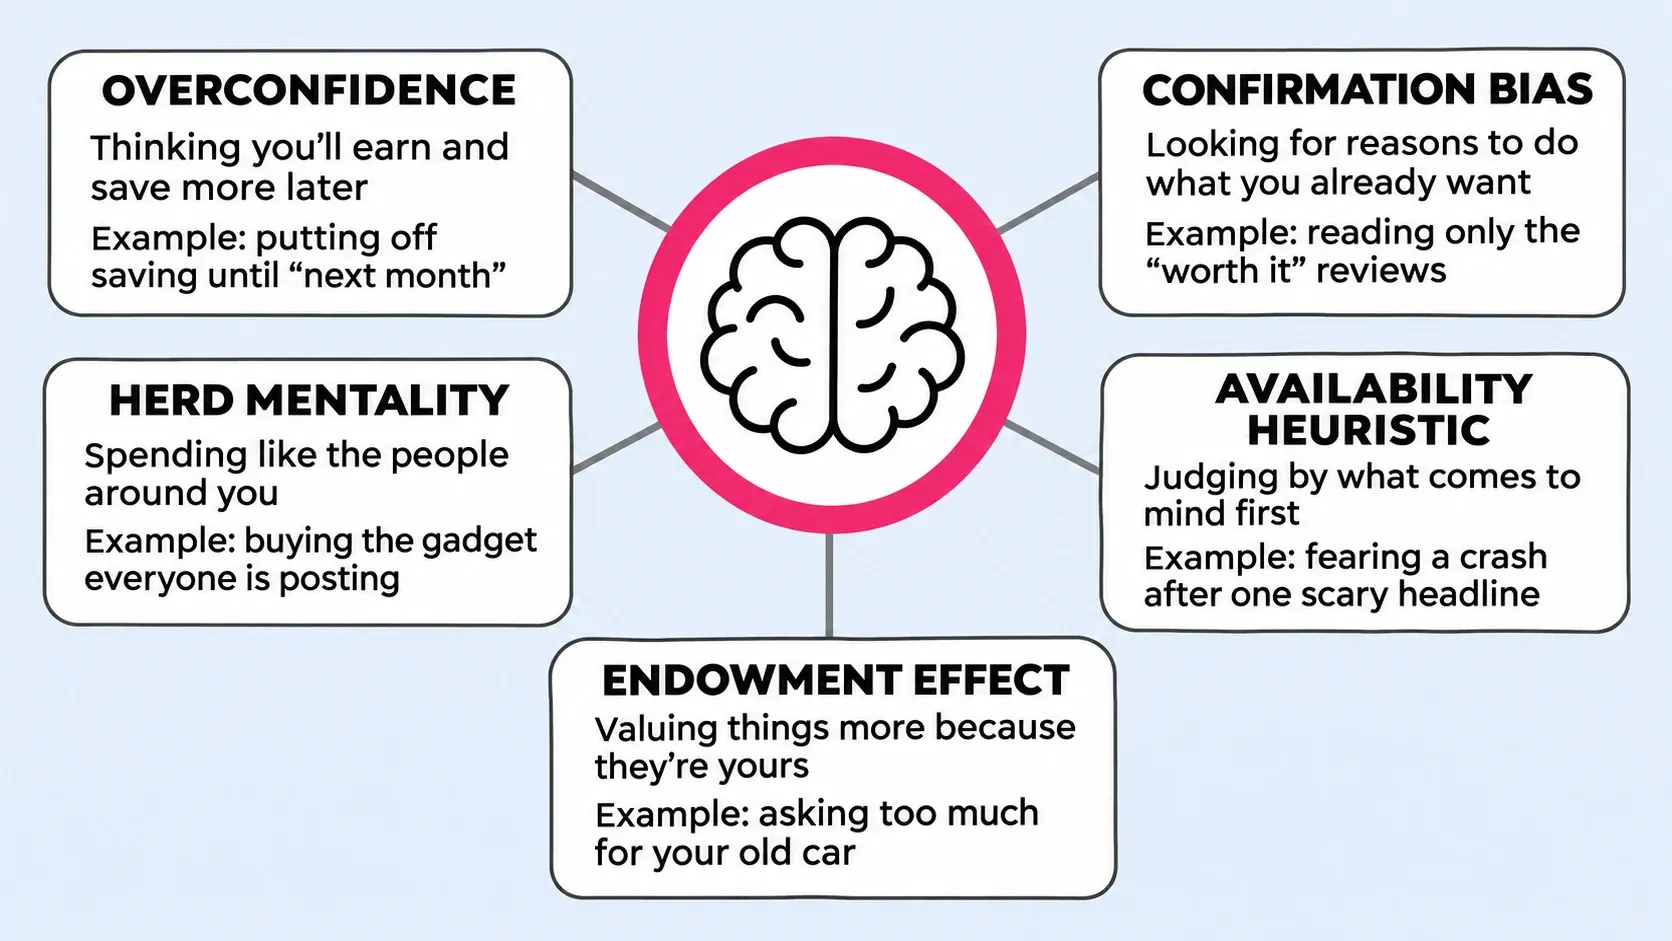
Herd mentality makes us follow what our circle spends, from the trendy gadget to the restaurant everyone is posting, often powered by fear of missing out. The question that gets skipped is whether it fits my budget. To find your own pressure points, try spotting your spending triggers.
Confirmation bias makes us look for reasons to do what we already want. If you want the expensive thing, your brain will find every review that says "worth it" and skip the one line in your budget that says "not now".
The availability heuristic makes us rely on whatever comes to mind most easily, usually something recent or vivid. A news story about a market crash makes investing feel terrifying, while a feed full of holiday photos makes a big trip feel normal. Neither tells you anything about your own odds or your own budget.
The endowment effect makes us value things more simply because we own them. In Kahneman, Knetsch and Thaler's famous coffee-mug experiments, people who had been given a mug asked roughly twice as much to sell it as others were willing to pay. It's why decluttering, downsizing or selling a losing asset feels so much harder than it should.
Your bias-proofing checklist
- For present bias, automate saving on payday, and commit part of every future pay rise in advance.
- For loss aversion, raise your saving rate the day income rises, so nothing feels taken away.
- For anchoring, set your price or budget before you see anyone else's number.
- For mental accounting, create labelled goal jars on purpose, and route windfalls into them first.
- For hedonic adaptation, add a waiting period to non-essential purchases.
- For the other five, ask before a big purchase whether you'd buy it if nobody could see it and it were not on sale.
None of these needs more willpower. Each one changes the setting the decision happens in, so the leaky wallet from the start of this article gets patched by design rather than by effort. Part II covers the outside forces (social pressure, how we pay) and builds these moves into a full saving system.